
Blogs
PW Consulting: HIFU Market Hits $215M in 2025, Forecasts 7.25% CAGR to $344.8M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the High-Intensity Focused Ultrasound System Market: A 2026 Outlook
The High-intensity Focused Ultrasound (HIFU) System Market stands at a critical inflection point as the global healthcare landscape shifts toward non-invasive, precision-based therapeutic modalities. With a total market valuation reaching 215.0 USD Million in the base year and projected to ascend toward 344.8 USD Million by the close of the forecast window, the sector is demonstrating robust structural momentum. Our latest comprehensive market study distills this trajectory into actionable intelligence, enabling executives to navigate the complex interplay of regulatory evolution, clinical adoption, and technological differentiation that will define competitive positioning through 2032.
For strategic decision-makers operating in medtech, hospital procurement, or venture-backed healthcare innovation, this report functions as a navigation blueprint. It maps the current revenue topology, isolates the primary growth vectors, and evaluates how market participants are aligning product portfolios with emerging reimbursement signals. The analysis is structured to deliver clarity without noise, emphasizing operational readiness over superficial trend-chasing. As we enter 2026, the convergence of clinical evidence maturation, payer documentation standardization, and platform-specific regulatory clearances demands a more granular understanding of where capital, R&D, and commercial resources should be deployed.
Macro Trajectory and Growth Architecture
The historical record from 2020 through 2025 reveals a consistent upward climb, with revenue scaling from 163.15 USD Million to 215.0 USD Million. This expansion was not merely a function of incremental adoption; it reflects a structural reorientation in how health systems evaluate procedural risk, recovery timelines, and long-term patient throughput. Forecasts extending through 2032 indicate a compound annual growth rate of 7.25 percent, signaling sustained demand expansion rather than a temporary surge. The forward curve suggests that early movers who secure clinical workflow integration, streamline installation and service models, and align with payer documentation requirements will capture disproportionate share during the mid-forecast period.
Growth is being propelled by several intersecting forces. Clinicians and hospital administrators are increasingly prioritizing therapies that reduce inpatient burden, minimize collateral tissue damage, and offer repeatable treatment protocols without ionizing radiation. Simultaneously, device manufacturers are compressing form factors, enhancing imaging-fusion capabilities, and building robotic assistance layers that standardize targeting accuracy. These technological refinements are lowering the barrier to entry for new clinical sites while expanding the addressable patient population across both therapeutic and aesthetic indications. The result is a market that is widening in scope even as it deepens in technical complexity.
Report Content and Operational Utility
Our analysis is engineered to translate market signals into execution-ready insights. Rather than offering abstract commentary, the report delivers a structured dossier of operational components that senior leadership can immediately integrate into commercial planning, investment committee memos, and product roadmap reviews. The study covers the following core modules:
- Comprehensive revenue mapping across historical baselines and forward-looking forecast intervals, with explicit identification of inflection years where adoption velocity is expected to accelerate.
- End-to-end segmentation analysis that dissects market structure by clinical and commercial categories, highlighting how therapeutic platforms, aesthetic applications, and compact system architectures are carving distinct growth lanes.
- Regional deployment patterns and purchasing ecosystem characteristics, enabling localization strategies for distribution partnerships, clinical training programs, and service infrastructure planning.
- Technology and workflow evaluation frameworks that assess imaging integration, targeting precision, treatment duration, and operator dependency across competing platform types.
- Reimbursement and policy tracking modules that consolidate CPT coding references, national health system coverage decisions, and payer medical policy updates into a single decision-support environment.
- Competitive benchmarking and strategic positioning maps that evaluate product differentiation, clearance trajectories, clinical collaboration networks, and geographic footprint strength.
Each module is designed to reduce ambiguity in capital allocation and market-entry timing. For organizations evaluating expansion into new indications, the report isolates the clinical evidence thresholds and procedural familiarity curves that typically govern adoption speed. For established players refining go-to-market execution, the analysis surfaces workflow bottlenecks, service-model gaps, and training requirements that often determine realized utilization rates. The synthesis of clinical, regulatory, and commercial layers ensures that leadership can evaluate opportunities through a unified lens rather than fragmented siloed data.
Competitive Landscape and Strategic Positioning
The HIFU ecosystem is characterized by a concentrated yet dynamically evolving competitive field. Market concentration metrics indicate that a small cohort of established players commands a dominant share of total revenue, reflecting the high technical thresholds, regulatory navigation requirements, and clinical validation cycles that typically accompany focused ultrasound platform commercialization. Within this structure, differentiation is increasingly driven by indication-specific pipeline depth, imaging and workflow integration, and the ability to secure timely reimbursement alignment.
Several organizations exemplify the strategic pathways shaping the market. EDAP TMS SA has advanced its Focal One robotic HIFU system for prostate cancer focal therapy, reinforcing its position through recent imaging and workflow enhancements that received FDA 510(k) clearance, alongside France’s national universal health system reimbursement decision for the Focal One procedure. This dual momentum illustrates how product refinement and reimbursement alignment can compound commercial traction in a core urologic application. Theraclion continues to extend its footprint with the Echopulse and SONOVEIN robotic HIFU platforms, targeting non-invasive treatment pathways for thyroid nodules, breast fibroadenomas, and varicose veins, thereby broadening the indication map beyond traditional tumor ablation into benign and vascular applications.
Insightec maintains a distinctive position through its Exablate and Exablate Neuro systems, leveraging MR-guided focused ultrasound for essential tremor, Parkinson’s disease, and pain palliation. The neurological and functional applications associated with this platform highlight a growing premium segment where procedural precision and image-guided targeting command higher clinical scrutiny and specialized adoption pathways. Profound Medical Corp. contributes to the therapeutic landscape with the Sonalleve MR-HIFU platform, supporting prostate cancer ablation and osteoid osteoma treatment, while also expanding into related oncologic applications that benefit from precise thermal ablation capabilities.
Chongqing Haifu Medical Technology Co., Ltd. represents an important distribution and manufacturing axis, with JC and JC200 HIFU systems supporting non-invasive tumor ablation across liver, breast, and bone applications as well as benign conditions, backed by global distribution reach. This international footprint underscores how regional manufacturing strength and export-oriented commercial networks can influence global supply dynamics and pricing architecture. Sonablate Corp. continues to develop the Sonablate 450 HIFU system for prostate cancer treatment, supported by ongoing clinical collaborations and product distribution, reinforcing the sustained focus on urologic ablation as a foundational market pillar. Meanwhile, FUSMobile, Inc. has carved a specialized niche with the Neurolyser XR fluoroscopy-guided HIFU system for chronic low back pain treatment, recently obtaining De Novo clearance that opens a distinct pain-management pathway and demonstrates how targeted nerve-destruction applications can diversify the overall demand base.
Regulatory and Reimbursement Dynamics as Strategic Catalysts
Market expansion in focused ultrasound is increasingly contingent on the alignment between clinical evidence, procedural coding clarity, and payer acceptance. Recent developments show that reimbursement infrastructure is moving from fragmented, institution-specific decision-making toward more standardized documentation expectations. Anthem Medical Policy CG-MED-81, updated in early 2026, lists applicable CPT codes for HIFU ablation procedures, reinforcing coding visibility for commercial payers and creating a more predictable billing environment for providers. This type of policy clarity reduces administrative friction and supports broader site-level adoption, particularly for centers that depend on consistent outpatient reimbursement pathways.
At the same time, reimbursement strategy has become an active commercial priority rather than a passive compliance function. Industry participants are investing in education and documentation guidance to help clinical sites navigate coding requirements and submission accuracy. This is reflected in recent webinar initiatives focused on the evolving reimbursement landscape and the documentation needed for accurate billing, signaling that market maturity now includes payer-facing readiness as a core capability. The existence of CPT code 55880 for transrectal high-intensity focused ultrasound prostate ablation, which has supported Medicare outpatient reimbursement since 2021, further illustrates how coding stability can anchor long-term utilization patterns in a key therapeutic segment.
Regulatory milestones are also reshaping competitive timing. Recent FDA clearances for imaging and workflow enhancements, as well as De Novo clearance for nerve-targeted chronic low back pain treatment, demonstrate that the regulatory pathway is enabling both incremental platform refinement and new indication entry. In parallel, broader ecosystem developments such as the establishment of an international focused ultrasound society are helping to standardize clinical practice, convene evidence generation, and accelerate adoption through shared professional infrastructure. These dynamics suggest that the organizations most likely to compound advantage in 2026 and beyond will be those that synchronize product development with reimbursement documentation, clinical education, and professional society engagement.
High Intensity Focused Ultrasound (HIFU) Market
Implications for 2026 Decision-Making
For executives planning 2026 strategic moves, the market presents a clear mandate: prioritize positioning that aligns product capability with reimbursement readiness, clinical workflow compatibility, and indication-specific evidence maturity. The compound growth trajectory implies that demand will continue to broaden, but the pace of capture will differ substantially across segments depending on how quickly sites can integrate the technology into existing procedural pathways. Organizations that treat reimbursement and coding clarity as a core commercial pillar, rather than a downstream administrative concern, will gain faster utilization ramp and more predictable revenue conversion.
The report provides the structural context required to make these choices with confidence. It maps where concentration is highest, where emerging applications are gaining traction, and how recent regulatory and reimbursement actions are reshaping site-level purchasing behavior. By situating these insights within a forward-looking framework, the study enables leadership to identify which therapeutic platforms, aesthetic devices, and compact system architectures warrant deeper investment, partnership development, or geographic prioritization. It also supports scenario planning around clinical education, service expansion, and workflow integration, ensuring that strategic intent is matched by operational readiness.
High-intensity Focused Ultrasound System Market
Ultimately, the High-intensity Focused Ultrasound System Market is evolving from a niche therapeutic category into a broader precision-treatment ecosystem. The organizations that will define the next phase of competitive advantage are those that can read the convergence of technology, regulation, and clinical adoption with precision and act on it quickly. This research is designed to give leadership that clarity, equipping decision-makers with the context needed to convert market momentum into durable strategic positioning through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: High-intensity Focused Ultrasound System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microbial ID Market Hits $327.2M in 2025, Set to Reach $600.3M by 2032
By pmarketresearch, 2026-09-15
Navigating the Next Wave: Strategic Intelligence for the Microbial Identification Market Beyond 2026
The global landscape for microbial identification is undergoing a structural transformation. What was once a niche laboratory function has evolved into a critical infrastructure component for clinical diagnostics, pharmaceutical quality control, and food safety assurance. As the industry approaches the mid-2026 inflection point, the complexity of regulatory expectations, the acceleration of analytical speed, and the commercialization of rapid identification workflows are converging to reshape competitive dynamics. This article distills the strategic essence of our latest Microbial Identification Market research, designed to equip executives, procurement leaders, and product strategy teams with the contextual intelligence required to navigate the 2026-2032 horizon with confidence.
Understanding where the market is heading is no longer a luxury reserved for R&D teams. It is a boardroom imperative. The decisions being made today regarding instrumentation adoption, database licensing, service-level agreements, and regional expansion will determine whether organizations capture the compounding value of a rapidly maturing ecosystem or fall behind fragmented, slower-moving competitors. Our new analysis provides a rigorous, forward-looking framework to support those decisions, combining historical trajectory modeling, technology adoption curves, and competitive intelligence into a single actionable reference.
Market Trajectory: From Modest Growth to Sustained Expansion
The decade preceding 2026 has established a clear upward baseline for microbial identification. Revenue across the global market progressed from a foundational level in 2020 and climbed steadily through the middle of the decade, reflecting broader adoption of rapid phenotypic and genotypic identification platforms across integrated laboratory networks. By 2025, the industry reached an estimated valuation that underscored the shift from early-adopter experimentation to routine operational deployment.
Looking forward, the projection for 2026 places the market at a new threshold, with sustained momentum carrying the total addressable size through the end of the forecast window. The compound annual growth rate over the 2026-2032 period is projected at 9.07 percent, a pace that signals durable demand rather than a temporary peak. Growth will be driven by multiple reinforcing forces: the increasing integration of microbial identification into antimicrobial stewardship programs, the standardization of quality control workflows in pharmaceutical manufacturing, and the expanding expectations for traceability in food and environmental testing.
Notably, the trajectory does not follow a simple linear path. The forecast reflects periods of consolidation, technology-driven step changes, and regional adoption variation that will reward organizations capable of timing their investments to match the rhythm of clinical and industrial procurement cycles. Executives who rely on single-point estimates or static snapshots risk misallocating capital. A structured, multi-scenario view of how the market scales through 2032 is essential for capacity planning, partnership strategy, and M&A screening.
Segmentation Dynamics: Where Value Is Concentrated and Where It Is Emerging
The structure of the microbial identification market is defined by meaningful concentration in specific technology classes, application domains, and geographies. While the overall market expands, value is not distributed evenly across all categories. The research maps how distinct platforms and use cases capture disproportionate share, shaped by regulatory clearance timing, laboratory workflow compatibility, and the breadth of organism coverage each solution can support.
Technology leadership continues to be anchored by high-throughput analytical approaches that deliver rapid turnaround with minimal sample preparation. Within the broader portfolio of methods, certain categories command a larger share of the revenue pool, while complementary approaches serve specialized laboratories or regional procurement preferences. The segmentation analysis in our research dissects these balances without oversimplifying them, helping teams understand not only which categories lead today but which are gaining relative momentum as database content, automation, and software integration evolve.
Application-driven demand reveals an equally layered picture. Clinical diagnostics remains the most prominent use case, reflecting the centrality of organism identification in patient care pathways and antimicrobial susceptibility testing. Pharmaceutical manufacturing quality control represents a substantial and growing share, driven by rigorous contaminant control requirements and batch-level traceability mandates. Food safety and environmental monitoring contribute additional, structurally distinct demand streams, each with its own throughput expectations, validation requirements, and service models.
A critical strategic insight from the segmentation work is that the relative weight of each application and technology category is not static. As automated workflows mature and software layers become more deeply integrated into laboratory information systems, the practical meaning of segmentation shifts. A platform that appears dominant in one year can see its relative position adjusted by database expansion, regulatory milestones, or interoperability improvements. Our analysis tracks these dynamics in a way that lets organizations anticipate shifts rather than react to them after reallocation has already occurred.
Microbial Identification Market
Geographic deployment patterns further shape where investments will pay off most efficiently. Certain regions exhibit larger baseline demand and more mature procurement environments, while others present faster relative growth trajectories as laboratory infrastructure modernizes. The research provides regional nuance at a level of granularity that supports multi-market entry planning, distribution partnership evaluation, and localization of service offerings, while preserving the confidentiality of the exact split figures that our clients obtain in full.
Competitive Differentiation: Bruker Corporation and bioMérieux as Strategic Anchors
The competitive environment for microbial identification is concentrated, yet it is far from static. A handful of established players shape the direction of technology standards, regulatory expectations, and customer operating norms. Among them, Bruker Corporation and bioMérieux stand out as companies whose product strategies and recent milestones illustrate how leadership is being contested and defended in the current cycle.
Bruker Corporation, headquartered in Billerica, Massachusetts, has focused its identification strategy on the MALDI Biotyper CA System, leveraging FDA-cleared MALDI-TOF mass spectrometry for rapid identification of gram-positive and gram-negative bacteria, anaerobes, and yeasts from cultured isolates. The platform’s value proposition extends beyond raw identification speed; it includes MBT Compass HT CA software, which is designed to streamline laboratory workflows and reduce manual handling steps. This emphasis on workflow efficiency reflects a broader industry trend in which instrumentation must prove not only analytical performance but also operational fit within highly constrained laboratory schedules.
In October 2025, Bruker received FDA clearance for Claims 7 and 8 of the MALDI Biotyper CA System, expanding the cleared reference library to 549 species and introducing MBT FAST Shuttle US IVD and MBT Compass HT CA software. From a strategic standpoint, this clearance matters because it broadens the population of organisms that laboratories can confidently identify within a cleared workflow, potentially increasing the system’s relevance across both clinical and industrial settings. Database breadth and software integration are increasingly important differentiators, and this milestone illustrates how platform maturity can be extended without changing the underlying hardware category.
bioMérieux, based in Marcy-l’Étoile, France, pursues a similarly focused but distinct approach. Its VITEK MS PRIME and VITEK COMPACT PRO systems combine FDA 510(k)-cleared MALDI-TOF with automated identification and antimicrobial susceptibility testing workflows, targeting both clinical and industrial microbial identification. A distinguishing feature of bioMérieux’s offering is the expanded database capability for mycobacteria, molds, and resistant pathogens, which directly addresses laboratories’ need to manage organisms that are historically slower or more difficult to identify with confidence.
In March 2025, bioMérieux secured FDA 510(k) clearance and launched the VITEK COMPACT PRO ID/AST system for rapid microorganism identification and antibiotic susceptibility testing in clinical and industrial laboratories. This development reinforces the company’s positioning at the intersection of identification and downstream testing, an integration that matters to laboratories seeking to compress turnaround times while preserving interpretive context. For organizations comparing platform options, these types of integrated workflows can influence total cost of ownership, space utilization, and staffing requirements.
Both companies demonstrate that the competitive battleground is increasingly defined by cleared use cases, database coverage, software-driven efficiency, and the ability to serve multiple end-use environments without compromising validation or reproducibility. For executives evaluating vendor relationships, understanding these differential strengths is more valuable than comparing instrument lists in isolation. Our research analyzes each player’s strategic posture, recent development history, and likely direction of travel, providing the context needed to interpret vendor claims against market realities.
Regulation, Standards, and the Shaping of Market Access
Regulatory and standards frameworks are not merely compliance issues; they are market-shaping forces. In microbial identification, the interaction between clearance pathways, certification requirements, and reimbursement mechanisms influences which solutions gain commercial traction, how quickly they scale, and which laboratories are willing or able to adopt them.
One of the most consequential dynamics for the United States market is the relationship between FDA 510(k) clearance and reimbursement through CPT codes. When a microbial identification test aligns with clearance expectations and coding structures, the path from laboratory adoption to sustainable financial operation can become materially smoother. This linkage is especially important for clinical laboratories that must justify capital expenditure and recurring consumables within tightened operating budgets.
Beyond clearance, quality system expectations such as ISO 13485 certification remain central to medical-grade systems. Laboratories and procurement teams increasingly view certification as a baseline indicator of process discipline and reliability, particularly where identification results feed directly into regulated workflows. In pharmaceutical manufacturing and clinical environments, the credibility of a platform often depends as much on its quality infrastructure as on its analytical output.
Regulatory developments also intersect with broader institutional priorities such as antimicrobial stewardship. Clearance milestones for ID/AST-capable systems support laboratory use cases that help stewardship programs act on identification and susceptibility information more quickly. This alignment between technology and institutional mission can be a significant adoption driver, because it gives laboratory leadership a narrative that extends beyond instrument performance to organizational impact. These dynamics are explored in detail in the report’s market dynamics section, where regulatory events are linked to adoption consequences and commercial timing.
What the Research Delivers: Operational Intelligence for Decision-Makers
This market research is structured to function as a working strategic asset, not a static summary. It is designed for teams that need to translate market knowledge into procurement timing, product planning, regional prioritization, and competitive positioning. The report’s operational value rests on several interrelated components.
First, the report provides a full historical and forecast view of market size and growth, including the underlying trajectory that connects the 2020 baseline through the 2025 reference year and out to 2032. This multi-year structure supports capacity planning, demand forecasting, and revenue modeling with a consistent analytical basis.
Second, the segmentation analysis breaks down technology types, application areas, and regional deployment patterns in a way that allows clients to assess where opportunity is concentrated and where differentiation is most achievable. The segmentation framework is built to reveal relative positioning and growth intensity, helping teams determine whether to compete in crowded categories or pursue higher-margin, faster-growing niches.
Third, the competitive landscape assessment profiles major participants and maps their strategic moves, recent clearances, product updates, and market focus. This section is intended to support vendor evaluation, partnership screening, and competitive threat analysis. Where relevant, it also highlights how product-level developments interact with broader market trends such as database expansion, workflow automation, and cleared-use-case expansion.
Fourth, the report examines market dynamics, including regulatory drivers, reimbursement linkages, quality standards, and stewardship-related adoption pressures. By connecting policy and standards to commercial behavior, the analysis helps teams anticipate demand shifts that may not be visible in headline market size alone.
Finally, the research incorporates strategic interpretation layers that translate data into decision readiness. Rather than leaving the reader with isolated figures, it provides the reasoning needed to evaluate entry timing, regional prioritization, technology mix, and competitive exposure. The full study preserves a level of detail that enables direct application to internal models, while the present article intentionally focuses on the strategic framework and the nature of the intelligence available.
Why This Research Matters for 2026 Decisions
The 2026 decision window is particularly important because it sits at the intersection of several compounding forces. Market growth is robust enough to reward early positioning, yet fast enough that delays can result in missed share and higher acquisition costs. Technological progress is material, with cleared databases and software-driven workflows expanding the practical value of established platforms. Regulatory and reimbursement dynamics are entering a more influential phase, increasing the importance of clearance status, certification, and coding alignment in adoption decisions.
In that environment, organizations need more than a forecast number. They need a defensible view of how growth is distributed, where competitive intensity is rising, how regulation will shape access, and which vendor strategies indicate durable advantage versus short-cycle positioning. The research is built to provide that view. It supports capital allocation, vendor selection, market entry sequencing, and product roadmap planning by grounding them in a consistent, evidence-based market structure.
Executives who act on this intelligence early can shape their strategies around the market’s actual contours rather than its visible headline. That includes deciding where to compete on workflow integration, where to invest in database and coverage breadth, where to emphasize service and validation support, and where to avoid overcommitting to categories that are likely to face margin pressure or substitution risk. The report is designed to make those choices more deliberate and less reactive.
Microbial Air Samplers Market
Conclusion: Strategic Clarity for a Market in Motion
The microbial identification market is entering a phase in which analytical performance, workflow efficiency, regulatory alignment, and commercial execution will separate durable players from marginal ones. The growth trajectory through 2032, the 9.07 percent CAGR, and the multi-category concentration of demand all point to an environment rich with opportunity but demanding in execution. Organizations that understand the structure of that environment will be better placed to allocate resources, choose partners, and time their moves.
This article has outlined the strategic logic behind the new market research and described the types of insight it provides for 2026 decision-making. To obtain the complete segmentation data, forecast detail, competitive profiles, and dynamic analysis needed for internal planning, we invite you to access the full report and its supporting materials. The remainder of the market’s specific composition, regional balances, and precise category values are presented in full within the study, where they can be used directly for modeling, benchmarking, and strategic planning.
For detailed analysis of this topic, please visit the official page: Microbial Identification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rupture Disc Market Hits $678.2M in 2025, Projects $874.6M by 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Rupture Disc Market: Navigating Growth and Compliance Through 2032
The global industrial landscape is undergoing a profound transformation, driven by tightening safety regulations, evolving material science, and an unwavering focus on operational integrity. Within this complex ecosystem, pressure relief systems remain a cornerstone of process safety management, with the rupture disc standing as a critical, non-reclosing device designed to protect equipment from exceeding allowable pressure limits. As organizations look toward the 2026 fiscal year and beyond, the ability to anticipate market shifts, understand competitive maneuvers, and align procurement strategies with regulatory trends is no longer optional—it is a strategic imperative. This analysis draws from the latest comprehensive market study on the Rupture Disc Market, offering a high-level view of the trajectory defined by data spanning from 2020 through the forecast horizon of 2032.
Market Trajectory and Macroeconomic Signals
The rupture disc market has demonstrated resilience and steady expansion over the past half-decade, reflecting the broader industrial demand for reliable pressure management solutions. Historical data from 2020 to 2025 reveals a trajectory of measured growth, with the global market valued at approximately 597.5 million USD in 2020. Despite minor fluctuations in the early years, the market strengthened through 2023 and 2024, reaching a valuation of 646.06 million USD before continuing its upward trajectory to an estimated 678.2 million USD in the 2025 base year. This historical consolidation sets the stage for an accelerating growth phase, with projections indicating a compound annual growth rate (CAGR) of 3.7 percent over the forecast period from 2026 to 2032.
By 2026, the market is anticipated to surpass the 722 million USD threshold, with growth compounding annually to reach a projected valuation of 874.6 million USD by 2032. This sustained expansion is underpinned by continuous investments in industrial infrastructure, heightened awareness regarding pressure vessel safety, and the indispensable role of rupture discs in preventing catastrophic failures across high-risk environments. For strategic planners and procurement leaders, these macro-level figures are not merely statistics; they are indicators of market maturity and opportunity. Understanding the pace and volume of this growth allows enterprises to calibrate their capacity planning, investment timelines, and risk mitigation frameworks with precision, ensuring they remain competitive in a sector that values reliability and compliance above all else.
Segmentation Dynamics: Materials and Applications Driving Demand
A deeper examination of the market structure reveals distinct preferences and performance drivers across material classifications and end-use applications, shaping the strategic landscape for manufacturers and buyers alike. The market is fundamentally bifurcated by material composition, where metallic rupture discs command a dominant share of the revenue landscape, reflecting their widespread adoption in high-pressure and high-temperature industrial environments where structural integrity and burst precision are paramount. Graphite and non-metallic variants, while representing smaller portions of the total market value, hold significant strategic importance in specialized applications involving highly corrosive media or extreme thermal conditions where metallic alternatives may be compromised. The demand for graphite solutions, in particular, underscores a growing industry need for materials that offer temperature-independent properties and resistance to chemical degradation, aligning with the operational realities of modern processing facilities.
In parallel, the application spectrum illustrates the diverse utility of rupture discs across critical industrial verticals. The oil and gas sector remains a substantial contributor to market revenue, driven by the relentless demand for overpressure protection in exploration, refining, and pipeline infrastructure. The chemical processing industry follows as another major pillar, leveraging rupture discs to maintain safety standards in reactors, storage vessels, and distillation columns where hazardous substances are handled. Meanwhile, the pharmaceutical and biotechnology segments are experiencing notable strategic relevance, fueled by stringent hygiene requirements and the adoption of sanitary designs that ensure cleanability, sterilization compatibility, and traceability. Other application areas further diversify the market, encompassing food and beverage processing, extrusion operations, and general industrial processes that require reliable pressure relief without compromising product purity or process efficiency. For decision-makers, recognizing which verticals are driving volume and which materials are gaining traction in specific process conditions is essential for tailoring product portfolios and supply chain strategies.
Regulatory Pressures and Technical Standards as Growth Catalysts
The rupture disc market is inextricably linked to an evolving regulatory environment, where compliance is not a static checkbox but a dynamic requirement that shapes product development, procurement criteria, and operational validation. Leading manufacturers are increasingly aligning their product portfolios with rigorous international standards, ensuring that their devices meet the exacting demands of modern processing facilities. Sanitary rupture discs, for instance, are being engineered to comply with ASME BPE, USP Class VI, and 3A standards, addressing the critical needs for traceability, cleanability, and sterilization in pharmaceutical and biotech environments. These compliance frameworks are not merely administrative; they directly influence the selection of disc types, the validation of installation procedures, and the long-term maintenance protocols that facilities must adhere to in order to pass regulatory audits and maintain operational licenses.
Rupture Disc Market
In the food, beverage, and pharmaceutical sectors, the emphasis on hygiene and process safety has accelerated the adoption of hygienic rupture discs that are compatible with Clean-in-Place and Sterilize-in-Place procedures, while also offering vacuum resistance necessary for sterilization conditions. Similarly, graphite-based solutions are being validated for FDA conformance in applications involving corrosive media, with material properties that remain stable across temperature variations. Beyond end-product certifications, the industry is witnessing a push toward rigorous raw material traceability and in-house lot qualification testing that exceeds standard ASME and ISO code requirements for cycle life and burst tolerance. This heightened focus on material provenance and performance verification creates a competitive differentiator for manufacturers who can demonstrate superior quality control, while simultaneously raising the bar for buyers who must ensure that their pressure relief assemblies meet both operational and regulatory benchmarks. For strategic organizations, staying ahead of these regulatory currents requires continuous engagement with industry standards, proactive collaboration with equipment suppliers, and a comprehensive understanding of how compliance mandates will evolve through the forecast period.
Competitive Landscape and Strategic Positioning
The rupture disc market is characterized by a moderately concentrated competitive environment, where a handful of established players command a significant portion of the market share, while specialized manufacturers and regional contenders compete on innovation, niche applications, and geographic reach. The collective presence of key industry participants underscores the importance of brand reputation, technical expertise, and product breadth in securing long-term customer relationships. Strategic analysis of the competitive field reveals that market leaders are increasingly differentiating themselves through targeted product expansions, enhanced catalog offerings, and the development of assembly-level solutions that simplify installation and improve overall process safety.
Several core enterprises exemplify the strategic directions shaping the market. Continental Disc Corporation, based in Liberty, Missouri, has consistently reinforced its market position by expanding its portfolio of high-performance reverse-acting and tension rupture discs, with a particular emphasis on sanitary offerings compliant with ASME BPE, USP Class VI, 3A, and ISO standards. The company's recent initiatives, including the expansion of its APX rupture disc line to accommodate larger sizes for demanding industrial applications, the launch of the HPX-CTG cartridge rupture disc assembly to streamline installation and enhance process safety, and the introduction of the APX family for high-performance overpressure protection, illustrate a clear strategic focus on delivering scalable, robust solutions that address evolving customer requirements. Fike Corporation, headquartered in Blue Springs, Missouri, has carved out a strong niche in hygienic rupture disc technology, offering designs such as the AXIUS SC, SHX, and RD540 SC, as well as extruder rupture disc devices that are compatible with CIP/SIP protocols for food, beverage, and pharmaceutical applications, while supporting both reverse-acting and forward-acting configurations to meet diverse process needs.
ZOOK Enterprises LLC, operating from Chagrin Falls, Ohio, has established itself as a global manufacturer providing metal and graphite rupture disks across reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional configurations, serving a broad spectrum of industries including chemical, pharmaceutical, extrusion, and food processing. BS&B Safety Systems, based in Tulsa, Oklahoma, continues to deliver comprehensive rupture disk devices and pressure relief solutions that span industrial and process safety applications, reinforcing its role as a provider of integrated safety systems. Technetics Group, located in Los Angeles, California, brings a focus on high-precision rupture discs and engineered components that contribute to advanced pressure relief systems. Completing the competitive mosaic is FDC Co., Ltd., based in South Korea, which contributes to the global supply landscape with rupture disc products including the KSRRL series designed for industrial pressure relief applications. The presence of such diverse players highlights the importance of evaluating not just product specifications, but also the strategic alignment of each supplier with regional requirements, material capabilities, and compliance documentation.
Market concentration metrics further illuminate the competitive structure, with the top three companies collectively accounting for approximately 49.5 percent of the market, and the top five players consolidating an even larger share at roughly 65.2 percent. This concentration pattern suggests that while the market remains accessible to specialized and emerging entrants, scale, credibility, and established distribution channels play a decisive role in capturing significant market volume. For buyers and investors, understanding this concentration dynamic is critical for assessing supply chain resilience, negotiating leverage, and the potential for competitive disruption. Strategic procurement decisions must therefore weigh the advantages of working with established market leaders who offer broad portfolios and global support against the opportunities presented by specialized manufacturers who may provide tailored solutions or competitive pricing in specific segments.
Forecast Outlook and Strategic Implications for 2026 and Beyond
Looking ahead to the 2026 forecast period and the subsequent years through 2032, the rupture disc market is positioned for sustained growth, but the pathways to value capture will require nuanced strategic planning. The projected trajectory indicates that while the overall market will expand steadily, the relative performance of different materials, applications, and regions will diverge based on localized industrial activity, regulatory enforcement intensity, and the pace of technological adoption. Enterprises that proactively map their operations against these evolving dynamics will be better equipped to allocate capital, optimize inventory, and forge partnerships that enhance both safety performance and cost efficiency.
Strategically, the emphasis for 2026 should center on several key imperatives. First, organizations must deepen their understanding of material selection criteria, recognizing that the choice between metallic, graphite, and non-metallic rupture discs is not merely a technical specification but a long-term decision that affects maintenance cycles, compliance records, and operational reliability in specific media environments. Second, the growing importance of sanitary and hygienic designs across pharmaceutical, biotechnology, and food processing sectors demands that buyers and suppliers align on validation protocols, cleanability standards, and sterilization compatibility to avoid costly retrofit or compliance gaps. Third, the competitive landscape calls for a balanced sourcing strategy that acknowledges the strength of concentrated market leaders while remaining open to specialized suppliers who can deliver differentiated value in narrow but critical application niches. Fourth, the trend toward integrated assembly solutions and simplified installation methodologies points to a broader industry shift toward lifecycle value over piece-price procurement, encouraging decision-makers to evaluate total cost of ownership, installation complexity, and long-term safety performance.
Furthermore, the forecast horizon presents opportunities for organizations that can anticipate regional demand shifts and adjust their supply chains accordingly. While the analysis of regional segmentation remains a detailed component of the full market study, the overarching principle is clear: growth will not be uniform, and strategic agility will be rewarded. Companies that invest in market intelligence, maintain robust vendor evaluation frameworks, and stay attuned to regulatory developments will be positioned to navigate the complexities of the forecast period with confidence. The data projected through 2032 serves as both a benchmark and a compass, guiding stakeholders toward decisions that align with long-term industry trajectories rather than short-term fluctuations.
Conclusion: Accessing Comprehensive Intelligence for Strategic Advantage
The rupture disc market stands at the intersection of safety, compliance, and industrial growth, offering a landscape where informed decision-making can yield significant competitive and operational advantages. The macro-level data, segmentation insights, regulatory trends, and competitive dynamics outlined here represent only the introductory layer of a much deeper analytical framework. For organizations seeking to translate these high-level signals into actionable strategies for 2026 and the forecast period through 2032, a granular understanding of specific market sizes, regional contributions, application breakdowns, material performance metrics, and detailed competitor profiles is essential. Such intelligence enables precise budgeting, targeted market entry, optimized product development, and risk-aware procurement strategies that align with both immediate operational needs and long-term growth objectives.
The full market research study provides a comprehensive examination of these dimensions, offering the depth and granularity required to move beyond general trends and into the specifics that drive real-world strategic outcomes. By exploring the complete dataset, stakeholders can uncover hidden opportunities, identify potential supply chain vulnerabilities, and benchmark their positioning against the broader industry landscape. The insights contained within the full report are designed to empower executives, procurement leaders, product managers, and investors with the clarity needed to make confident, data-backed decisions in a market where precision and reliability are paramount. We invite you to access the complete study to gain the full spectrum of intelligence necessary to navigate the rupture disc market with strategic foresight and operational excellence.
Abrasive Disc Market
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Market Hits $36.9B, 9.25% CAGR to $68.49B by 2032
By pmarketresearch, 2026-09-15
Unlocking Value in a Reshaping Landscape: Strategic Imperatives for the Dental Market Through 2032
The global dental sector is navigating a period of profound transformation. Driven by an aging population, expanding insurance coverage, and rapid technological integration, the market has demonstrated remarkable resilience and growth potential. For enterprise leaders, investors, and strategic planners, understanding the trajectory of this sector is not merely an academic exercise but a critical component of capital allocation and product roadmapping for the coming years.
Our latest comprehensive market research study offers a rigorous examination of the Dental Market, providing a data-rich foundation for decision-making in 2026 and beyond. This article serves as a strategic overview, highlighting the macro trends and competitive dynamics shaping the industry, while outlining the actionable intelligence contained within our full report.
Market Trajectory and Macro Growth Signals
The historical performance of the dental sector provides a robust baseline for forecasting future demand. Our analysis tracks market performance from 2020 through 2025, capturing the recovery patterns and sustained expansion following global economic disruptions. The convergence of post-pandemic oral health awareness, rising disposable incomes in emerging economies, and the aesthetic demands of a digitally native consumer base has created a compelling growth environment.
Looking ahead, the market outlook remains exceptionally strong. Our forecasts project continued double-digit expansion over the next several years, driven by consistent demand across multiple vectors. The compound annual growth rate (CAGR) of 9.25% during the forecast period (2026-2032) underscores the sector's momentum. This growth is not linear; it is punctuated by waves of innovation, shifts in care delivery models, and evolving regulatory frameworks. For organizations strategizing for 2026, these projections offer a clear signal: the market is expanding, and the window for securing competitive advantage is open.
Revenue projections indicate a steady climb toward significant valuation milestones by the early 2030s. The trajectory suggests that cumulative reinvestment in dental infrastructure, technology, and consumables will yield substantial returns for market participants who align their strategies with these growth vectors. Understanding the magnitude of this expansion is essential for capacity planning, R&D budgeting, and M&A evaluation.
Dental Material Market
Macro Dynamics Shaping the 2026 Operating Environment
While top-line growth is attractive, success in 2026 requires a nuanced understanding of the underlying dynamics that influence margin profiles, supply chain stability, and consumer behavior. Our report dissects these forces to provide a clear picture of the operational realities facing dental enterprises.
Dental Market
Economic Pressures and Reimbursement Realities
Financial sustainability remains a central concern for practice owners and dental service organizations (DSOs). Recent data from the ADA Health Policy Institute indicates that while provider reimbursement rates remained stable in late 2025, they have not kept pace with overall inflation and rising practice expenses. This gap creates pressure on profitability, necessitating operational efficiencies and value-based service offerings. Simultaneously, material costs are rising; prices for dental equipment and supplies increased by 5% from the beginning of 2025. Navigating these cost dynamics requires precise procurement strategies and a keen eye on vendor negotiations.
Labor Market Nuances
The workforce landscape is evolving with subtle but significant shifts. As of December 2025, the total number of jobs in dental offices saw a slight monthly contraction of 0.2%, yet the year-over-year trend remained positive with a 1.3% increase. This suggests a tightening labor market where talent retention and specialized skill development are becoming critical differentiators. Organizations must consider how staffing models, training investments, and automation can mitigate labor constraints while maintaining high standards of care.
Regulatory and Ethical Clarity
The regulatory environment continues to mature, adding layers of compliance that demand attention. In May 2025, the Dental Trade Alliance issued a revised U.S. Code of Ethics, providing greater clarity on interactions between manufacturers, distributors, and dental professionals. This update reinforces the importance of transparency and ethical engagement in commercial activities. Companies that proactively align their practices with these standards not only mitigate risk but also enhance their reputation and trustworthiness within the professional community.
Competitive Landscape: Incumbents, Innovators, and Consolidation
The dental market is characterized by a mix of established global leaders, specialized innovators, and robust distribution networks. Market concentration metrics indicate a moderately consolidated environment, with the top three players holding a CR3 of 42.8% and the top five reaching a CR5 of 48.2%. This structure suggests that while scale advantages exist, there is still significant room for differentiation and niche leadership.
Several key players define the competitive arena. Dentsply Sirona Inc., headquartered in Charlotte, North Carolina, stands as a leading global manufacturer of dental equipment, implants, restorative materials, and digital solutions. Their comprehensive portfolio positions them as a central force in both clinical delivery and practice management technology. Straumann Group, based in Basel, Switzerland, remains a global leader in dental implants, prosthetics, and regenerative products, leveraging strong clinical evidence and brand equity in high-value segments.
Innovation in orthodontics and digital workflows is exemplified by Align Technology, Inc. of San Jose, California. As the developer of Invisalign clear aligners and digital orthodontics technology, Align continues to drive shifts in treatment preferences and data-driven care. Ivoclar Vivadent AG, located in Schaan, Liechtenstein, and GC Corporation of Tokyo, Japan, are pivotal players in dental materials, ceramics, and restorative products, serving the essential needs of clinical procedures across diverse geographies. Coltene Group, Kerr Corporation, and 3M Oral Care round out a formidable field of manufacturers focused on consumables, endodontics, rotary instruments, and preventive solutions.
The distribution ecosystem is equally vital. Henry Schein, Inc., Patterson Companies, Inc., and Benco Dental Supply Company form a backbone of supply chain logistics, offering supplies, equipment, and services to a vast network of dental professionals. Henry Schein and Patterson provide full-service solutions that integrate technology and practice management, while Benco serves over 30,000 professionals across the United States with a localized, responsive approach. Additionally, organizations like Yankee Dental Congress facilitate trade and supplier networks, supporting the commercial infrastructure that keeps the market vibrant.
Recent developments highlight the pace of product innovation. In 2025, COLTENE Group launched six new innovations, including HySolate Liquid Dam for advanced gingiva protection and Kenda ShapeGuard for next-generation polishing. Kerr Dental introduced next-generation shaping solutions, pre-sterilized diamond burs, and bioceramic sealers, enhancing procedural efficiency. Dentsply Sirona expanded its digital ecosystem with a new implant product selection guide on its U.S. e-commerce platform featuring the DS OmniTaper Implant. Other players like Parkell and Garrison Dental Solutions also unveiled advanced composites and matrix systems, signaling a continuous stream of incremental improvements that cumulatively raise the bar for performance and patient experience.
Strategic Implications for Enterprise Decision-Makers
For executives preparing for 2026, the interplay of growth, cost pressures, and competitive intensity demands a multifaceted strategy. Our research identifies several critical focus areas:
- Product and Portfolio Alignment: With consumables representing a significant share of revenue and equipment driving long-term value, companies must balance their portfolios to address immediate clinical needs while positioning for digital and precision advancements. Understanding the specific revenue contributions and growth rates of each segment is essential for resource allocation.
- Geographic Diversification and Local Insight: Growth opportunities vary significantly across regions. While mature markets offer stability and high per-capita spend, emerging regions present volume potential and infrastructure development needs. A granular understanding of regional market sizes, maturity levels, and consumer preferences is required to tailor go-to-market strategies effectively.
- Channel and Distribution Optimization: The role of distributors is evolving from mere logistics to value-added partner ecosystems. Leveraging the strengths of major distributors and trade networks can enhance market reach and customer engagement. Decision-makers must evaluate channel partnerships based on service quality, geographic coverage, and alignment with brand positioning.
- Innovation and Time-to-Market: The frequency of product launches among key competitors underscores the need for agile R&D and rapid commercialization. Staying ahead requires not only technological superiority but also a deep understanding of clinical workflows and practitioner pain points.
- Risk Management and Compliance: With reimbursement pressures, cost inflation, and evolving ethical codes, a proactive approach to risk is non-negotiable. Building resilience into supply chains, monitoring reimbursement trends, and adhering to the highest standards of professional conduct are foundational to long-term success.
Inside the Research: What Our Full Report Delivers
This article provides a strategic snapshot, but the depth of insight required for confident decision-making lies in our comprehensive market research report. Designed for senior leadership, strategy teams, and investors, the study offers an exhaustive analysis of the Dental Market, encompassing historical performance, detailed forecasts, and segment-level intelligence.
The report delivers actionable content across multiple dimensions:
- Market Sizing and Forecasting: We provide precise revenue estimates and growth projections spanning the base year through the forecast period of 2032. The analysis captures the full trajectory of market expansion, enabling accurate budgeting and investment planning.
- Segmentation Analysis: The research breaks down the market by region, type, and end-user, revealing the distinct performance characteristics and opportunities within each segment. This granular view allows stakeholders to identify high-growth pockets, assess competitive intensity, and prioritize markets based on revenue potential and strategic fit.
- Competitive Profiling: Detailed company profiles examine the capabilities, market positions, and recent activities of key players. Our analysis goes beyond basic descriptions to evaluate strategic moves, product launches, and positioning tactics, offering a clear map of the competitive landscape.
- Industry Dynamics and Drivers: We explore the macroeconomic, regulatory, and technological factors influencing market behavior. This includes analysis of reimbursement trends, supply chain conditions, labor dynamics, and ethical standards, providing context for interpreting market data and anticipating shifts.
- Strategic Recommendations: Synthesizing data and qualitative insights, the report offers tailored recommendations for navigating the market. Whether the goal is market entry, product development, M&A target evaluation, or operational optimization, our findings provide a structured framework for action.
We deliberately withhold the granular percentage splits and exact monetary values for specific regions, product types, and end-user categories in this public overview. These critical data points are integral to precise financial modeling and strategic planning. Access to the full report ensures that decision-makers have the complete data set needed to build robust business cases and avoid assumptions that could undermine competitive positioning.
Conclusion: Positioning for the 2026 Horizon
The Dental Market is on a robust growth trajectory, supported by favorable demographics, technological advancement, and increasing emphasis on oral health. However, the environment in 2026 presents a complex mix of opportunity and challenge. Rising costs, reimbursement gaps, labor constraints, and a competitive landscape defined by both scale players and agile innovators require a sophisticated approach to strategy.
Our market research equips organizations with the intelligence to navigate this complexity with confidence. By combining macro-level growth signals with micro-level segment analysis, competitive intelligence, and dynamic industry context, the report serves as an indispensable tool for crafting strategies that capture value and sustain advantage. We invite you to explore the full findings to unlock the detailed data and insights necessary for informed decision-making in the year ahead and throughout the forecast horizon.
For detailed analysis of this topic, please visit the official page: Dental Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
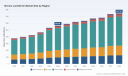
PW Consulting: Bovine Lactoferrin Market Hits $565.08M in 2025, Driven by Asia Pacific
By pmarketresearch, 2026-09-15
Navigating the Bovine Lactoferrin Market: Strategic Intelligence for 2026 and Beyond
The global bovine lactoferrin market stands at a critical inflection point. As demand for bioactive dairy proteins accelerates across infant nutrition, dietary supplements, and pharmaceutical applications, stakeholders require more than headline figures. They need a granular, forward-looking view of supply constraints, regulatory shifts, and competitive positioning. Our latest market research delivers precisely that intelligence, equipping leadership teams with the analytical rigor required to make confident capital allocation, product development, and partnership decisions throughout the 2026 to 2032 forecast horizon.
This report is engineered as a strategic compass. It translates historical trajectory, forward-looking projections, and on-the-ground industry signals into actionable frameworks. Decision-makers will find a structured assessment of market concentration, segmentation dynamics, production technology pathways, and the evolving regulatory landscape that will dictate commercial viability in key end-use sectors.
Bovine Colostrum Market
Market Trajectory and Structural Foundations
Historical performance from 2020 through the base year of 2025 demonstrates a consistent upward trajectory for bovine lactoferrin, reflecting sustained procurement by high-value nutrition and health applications. The market recorded steady revenue expansion across this period, moving from a baseline in the upper three-hundred-million range to a clearly elevated position as manufacturers scaled production and end-users integrated lactoferrin into core formulations. This historical momentum establishes a robust foundation for the forecast period extending through 2032.
Looking ahead, the market is projected to continue its measured expansion, sustained by multi-year investment in extraction capacity, growing acceptance of lactoferrin in specialized nutrition, and broadening application portfolios. The forecast period highlights a compound annual growth rate that underscores steady, compounding value creation rather than speculative volatility. Revenue growth will be shaped by the interplay of production scalability, feedstock economics, and the pace at which regulatory approvals unlock new geographic and application markets. Leadership teams planning capacity investments, pricing strategies, or market entry must anchor their models to this trajectory while remaining敏锐 to the structural variables that can accelerate or decelerate realization.
The report contextualizes these projections within a framework that separates durable demand drivers from short-term cyclical noise. By mapping the evolution from historical baselines to forward estimates, the analysis enables stakeholders to stress-test assumptions, calibrate inventory strategies, and align product roadmaps with the pace of market maturation.
Segmentation Dynamics and Application Realities
Bovine lactoferrin demand is distributed across multiple application vectors, each with distinct procurement cycles, quality requirements, and margin structures. Infant formula represents a substantial and structurally resilient demand center, driven by the protein's recognized bioactive profile and its integration into premium nutrition portfolios. Dietary supplements form another critical pillar, where lactoferrin's positioning within immune and gut-health formulations continues to attract formulation scientists and brand developers. Pharmaceuticals and food and beverage applications, while smaller in absolute contribution, represent high-growth vectors where regulatory clearance and functional validation will determine the pace of adoption. Additional use cases span specialized nutrition and emerging wellness categories, providing incremental demand that compounds as formulation expertise deepens.
Production technology also shapes segment economics. The market encompasses both freeze-dried and spray-dried processing pathways, each offering different trade-offs in purity retention, solubility, bulk density, and cost structure. Freeze-dried formats appeal to applications demanding maximum bioactivity preservation and stringent quality attributes, while spray-dried variants serve high-volume dry-mix and ingredient blending workflows where handling efficiency and cost competitiveness are paramount. Understanding which processing route aligns with specific end-use requirements is essential for procurement strategy, supplier selection, and product positioning.
Geographically, demand is distributed across a diverse set of regions, reflecting different stages of market development, regulatory environments, and consumer familiarity with bioactive dairy ingredients. Some regions exhibit mature procurement infrastructures and established supplier relationships, while others are in earlier phases of adoption where education, distribution building, and regulatory alignment remain active priorities. The report examines how these regional nuances influence sourcing strategies, channel development, and the timing of commercial rollouts, without reducing complex dynamics to simplistic rankings.
Competitive Landscape and Strategic Positioning
The bovine lactoferrin market is characterized by a mix of established dairy ingredient specialists, regional producers, and technology-forward entrants. Competitive intensity is moderated by meaningful barriers to entry, including the need for specialized extraction and purification capabilities, consistent access to high-quality milk feedstock, and the operational expertise required to maintain batch-to-batch consistency at commercial scale. These factors contribute to a moderately concentrated landscape where incumbency, process know-how, and supply chain reliability carry significant weight.
Several organizations anchor the competitive field. Armor Protéines, based in France, markets Vitalarmor® Lactoferrin in its native bovine form, with organic-grade variants targeting infant nutrition and dry-mix applications. Bega Cheese Limited leverages its broader dairy ingredients portfolio to supply bovine lactoferrin, integrating production with established milk processing operations. Fonterra Co-operative Group Limited provides lactoferrin through its Ingredients business, supported by continued investment in high-value product capacity that reinforces its role as a scalable supplier. Glanbia Plc delivers lactoferrin ingredients oriented toward nutrition applications, drawing on its global position in dairy-based nutritional solutions.
In Asia Pacific, Inner Mongolia Yili Industrial Group Co., Ltd. incorporates bovine lactoferrin into its dairy ingredients lineup, aligning production with regional demand centers and growing domestic nutrition markets. Milei GmbH stands out as a high-volume producer utilizing Morinaga process technology, giving it a distinct manufacturing footprint and supply capability. Morinaga Co., Ltd. has built long-term production and supply operations through subsidiary structures, emphasizing reliability and sustained commercial relationships. Noumi Limited markets PUREnFERRIN™, an ultra-premium native bovine lactoferrin derived from Australian whey, positioning on quality and provenance. Nutriscience Innovations, LLC operates as a U.S.-based supplier of bovine lactoferrin ingredients, serving formulation and distribution networks across North America.
Saputo Inc. produces bovine lactoferrin within its specialty ingredients range, benefiting from integrated dairy operations and established customer channels. Synlait Milk Ltd and Tatua Co-Operative Dairy Company Ltd both supply lactoferrin from dairy processing operations in New Zealand, capitalizing on the country's milk quality reputation and ingredient export infrastructure. Valfoo operates Switzerland's largest lactoferrin production facility, manufacturing Swissferrin® from fresh cow's milk and emphasizing domestic processing capability and quality control. Beston Global Food Company Ltd, based in Australia, manufactures high-purity bovine lactoferrin at its Jervois dairy factory, with capabilities reaching up to 95% purity, reflecting a focus on premium-grade output.
This competitive mosaic creates distinct strategic opportunities. Buyers must evaluate suppliers not only on price but on process consistency, regulatory documentation, capacity resilience, and the ability to support co-development or custom specification requirements. Suppliers, in turn, must differentiate through quality assurance, application expertise, and the strategic framing of their production technology and feedstock advantages.
2025 to 2026 Industry Dynamics and Catalysts
Recent developments illustrate how rapidly the competitive and regulatory environment is evolving. In late 2025, All G and Armor Protéines announced a joint venture to scale production and commercialization of human and bovine lactoferrin, with All G's first bovine lactoferrin powder product launching in late 2025. This partnership signals a broader trend toward structured collaborations that pair production capability with commercialization reach. Around the same period, All G raised more than A$10 million to support commercial-scale production, with its first bovine lactoferrin product targeted for launch in the first quarter of 2026, underscoring the capital intensity and execution risk associated with scaling novel ingredient supply.
Regulatory milestones are reshaping the addressable market. In May 2025, TurtleTree received the first no-questions letter from the FDA for precision-fermented bovine lactoferrin, enabling broader food and supplement use and opening a complementary pathway alongside traditional dairy-derived supply. This development aligns with the broader FDA GRAS notice issued on May 7, 2025, covering recombinant bovine lactoferrin isolate produced by Komagataella phaffii M020. Together, these regulatory actions expand the technical and commercial options available to formulators, while also introducing strategic questions about sourcing mix, labeling, and the long-term role of fermentation-derived ingredients relative to conventional dairy extraction.
Capacity expansion remains a central theme. Beston Global Food Company Ltd expanded lactoferrin production capacity at its Jervois dairy factory in Australia to up to 25 metric tons of 95% pure lactoferrin per year, a move that directly addresses supply constraints in the premium purity segment and reflects the strategic importance of dedicated processing lines. Such expansions signal that producers are actively aligning capacity with anticipated demand rather than relying solely on incremental throughput adjustments.
Regulatory and policy developments continue to influence market access and input economics. The European Union assessed bovine lactoferrin as a food ingredient in 2025 under Novel Food regulation, with evaluation covering uses in infant formula, supplements, and sports nutrition. The outcome of such assessments will shape the pace at which new application categories open in European markets. In China, the elimination of import tariffs on dairy-based formula foods for special medical purposes, effective in late 2023 and continuing into 2025, has implications for specialized nutrition procurement and cross-border ingredient flows. At the same time, the U.S. Department of Energy invested $9.7 million in alternative protein projects, including lactoferrin, to support decarbonization of the food sector, indicating that sustainability and production efficiency are increasingly being treated as strategic policy priorities rather than peripheral considerations.
Feedstock dynamics remain a persistent operational variable. High-quality bovine milk feedstock exhibits price volatility due to seasonal variations, feed costs, and global dairy market fluctuations. This volatility directly affects production economics and underscores the importance of feedstock sourcing strategy, hedging approaches, and supplier diversification for both ingredient manufacturers and downstream buyers.
What the Report Delivers: Analytical Architecture and Practical Utility
Our research is structured to move beyond descriptive summary and into decision-grade analysis. The report provides a comprehensive market sizing framework that integrates historical data with a multi-year forecast, enabling stakeholders to understand both the magnitude of the opportunity and the pacing of growth across the forecast window. Market concentration metrics are examined to clarify the extent to which revenue is distributed among leading participants and where consolidation, partnership, or niche positioning may create advantage.
Segmentation analysis is delivered in a format designed for practical application. Rather than treating categories in isolation, the report connects type, application, and regional demand patterns to procurement behavior, formulation requirements, and supply chain risk. This integrated view helps teams evaluate where to prioritize R&D, which customer segments warrant dedicated commercial resources, and how production technology choices influence margin and market access.
The competitive analysis goes beyond corporate profiling to assess strategic posture, differentiation levers, and the implications of recent capacity and partnership moves. By placing companies within the context of production capabilities, technology pathways, and regional footprints, the report equips stakeholders to map supplier suitability, anticipate competitive responses, and identify partnership or acquisition targets aligned with specific strategic objectives.
Regulatory and policy developments are tracked and interpreted with an eye toward commercial impact. The report translates regulatory milestones, tariff changes, and assessment processes into implications for market entry timing, formulation strategy, and sourcing architecture. This ensures that compliance considerations are treated as strategic inputs rather than afterthoughts.
Scenario and sensitivity considerations are embedded throughout. Feedstock volatility, regulatory approval timelines, capacity ramp-up risk, and the emergence of alternative production pathways are all factored into the analytical framework so that leadership can stress-test plans against plausible variations in the operating environment.
Strategic Imperatives for 2026 Decision-Making
As organizations move from planning to execution in 2026, several strategic imperatives stand out. First, sourcing strategy must balance quality, capacity, and resilience. With multiple processing technologies, purity grades, and supplier archetypes available, procurement teams need a structured method for matching supply characteristics to application requirements while safeguarding against feedstock and capacity disruption.
Second, product and formulation strategy should account for the expanding range of regulatory and technological options. The convergence of dairy-derived and precision-fermentation pathways is broadening the ingredient toolkit, and companies that evaluate these options early will be better positioned to optimize cost, functionality, and market positioning.
Third, competitive strategy should be anchored in differentiation that is difficult to replicate. Process know-how, application expertise, consistent quality documentation, and the ability to support customer co-development are likely to matter as much as price in a market where performance claims and regulatory compliance carry significant weight.
Fourth, geographic and channel planning should reflect the uneven pace of adoption and regulatory readiness across regions. Markets with established procurement infrastructures may reward scale and reliability, while earlier-stage markets may require education, distribution building, and carefully sequenced regulatory engagement.
Finally, capital and partnership decisions should be informed by a clear view of where market concentration, capacity expansions, and joint ventures are reshaping supply dynamics. The recent wave of investment and collaboration activity indicates that the market is entering a phase where strategic alignment between production capability and commercialization capacity will separate scalable participants from those constrained by fragmented or under-resourced operations.
Conclusion: Turning Intelligence into Execution
The bovine lactoferrin market offers meaningful long-term opportunity, but realizing that opportunity requires more than awareness of headline growth. It demands a clear understanding of segmentation realities, competitive positioning, regulatory direction, and the operational variables that shape cost and supply continuity. Our market research is designed to provide exactly that depth, translating complex industry signals into a structured basis for sourcing, product, and partnership decisions throughout the 2026 to 2032 period.
Organizations that approach the market with rigorous segmentation analysis, a clear view of supplier capabilities, and a forward-looking stance on regulatory and technology developments will be best placed to capture value as demand broadens and production capacity matures. This report delivers the foundational intelligence needed to build those strategies with confidence, while leaving room for tailored internal modeling and scenario planning.
For decision-makers seeking the full quantification, detailed segmentation breakdowns, company-level assessments, and forward-looking scenario analysis, the complete report is available for review. The full intelligence package extends beyond the overview presented here, providing the granular data and strategic frameworks required to translate market insight into executable plans.
Bovine Lactoferrin Market
For detailed analysis of this topic, please visit the official page: Bovine Lactoferrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Wheel Balancer Market Hits $242M in 2025, Projects 4.1% CAGR to 2032
By pmarketresearch, 2026-09-15
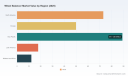
Strategic Balancing: Navigating the Wheel Balancer Market in 2026 and Beyond
The global automotive aftermarket ecosystem is undergoing a profound transformation, driven by tightening safety regulations, chronic labor shortages, and accelerating adoption of automated service equipment. Within this evolving landscape, wheel balancers have emerged as a critical node in the value chain, bridging vehicle safety compliance with operational efficiency in tire service facilities. Our latest comprehensive market research on the Wheel Balancer Market offers enterprise decision-makers a rigorous, forward-looking intelligence framework designed specifically to inform capital allocation, product development roadmaps, and competitive positioning strategies through 2032.
For executives operating in automotive service equipment, tire retail, fleet maintenance, or industrial manufacturing, the timing of this analysis is deliberate. The market has transitioned from a mature, price-driven segment into a technology-differentiated arena where precision, automation, and regulatory alignment dictate margin structures and customer retention. Understanding the underlying trajectories is no longer optional; it is a prerequisite for sustaining competitive advantage in an environment where workshop throughput, technician productivity, and safety compliance directly translate into revenue resilience.
Worldwide Wheel Balancer With Touchscreen Market
Macro Trajectory and Growth Architecture
Drawing on a consolidated historical dataset spanning 2020 through 2025, the market has demonstrated consistent expansion, culminating in a 2025 revenue baseline of 242.0 million USD. Projections extending through the 2026 to 2032 forecast horizon indicate a steady compounding trajectory, with an estimated compound annual growth rate of 4.1 percent. By the close of the forecast period, market valuations are positioned to approach 320.0 million USD. This growth profile reflects a sector that is neither undergoing explosive disruption nor facing structural contraction, but rather maturing through incremental technological upgrades, regulatory reinforcement, and regional capacity expansion.
The sustained upward momentum is fundamentally anchored in the dual pressures of vehicle safety enforcement and workshop labor economics. Mandatory periodic technical inspections under established regulatory frameworks continue to require precise wheel balancing as a non-negotiable compliance parameter. Concurrently, rising operational costs and persistent technician shortages are compelling service providers to invest in equipment that reduces cycle times and lowers labor intensity. Automation in balancing operations has therefore shifted from an optional efficiency measure to a strategic necessity, enabling facilities to maintain throughput without proportionally expanding headcount.
From a market structure perspective, concentration dynamics reveal a moderately consolidated landscape. Leading suppliers collectively command a significant share of total revenue, while the remaining portion is distributed across specialized manufacturers and regional equipment integrators. This concentration pattern suggests that scale advantages, brand recognition, and established service networks continue to differentiate veteran players, but also leaves room for targeted innovators who can address emerging demands in fleet-specific balancing, heavy-duty applications, and integrated diagnostic workflows.
Dimensioning the Opportunity Landscape
The market is structurally organized across equipment architecture, vehicle application, and geographic deployment. Each dimension carries distinct operational implications, pricing sensitivities, and adoption curves that directly influence procurement strategy and product portfolio design.
Equipment architecture represents the foundational strategic axis. Dynamic balancing systems continue to anchor the mainstream professional service segment, favored for their precision, compatibility with high-speed diagnostic routines, and alignment with standardized workshop practices. Static configurations retain relevance in specialized or budget-conscious settings, while bubble-based approaches occupy a narrower niche where manual processes and cost constraints dominate. The strategic implication is clear: procurement decisions increasingly weigh precision throughput against total cost of ownership, with automation-ready architectures capturing premium positioning as labor economics tighten.
Application segmentation further delineates demand drivers. Passenger vehicle servicing constitutes the dominant volume channel, reflecting the sheer density of light-duty fleets and the frequency of aftermarket tire maintenance. Commercial vehicle applications, while smaller in relative scale, present higher barriers to entry and greater value per installation, driven by fleet uptime requirements, heavy-duty load conditions, and specialized balancing needs. Companies that can bridge the requirements of both segments, or that can tailor solutions to one with clear differentiation, are better positioned to navigate demand volatility and expand addressable market share.
Regional distribution introduces additional complexity. North American and European markets are characterized by mature service networks, stringent safety standards, and strong aftermarket substitution demand. Asia Pacific represents a high-volume, rapidly expanding deployment zone where fleet growth, urbanization, and progressive formalization of service standards are accelerating equipment modernization. Latin American and Middle East and Africa regions operate with more variable regulatory maturity and purchasing power, yet they remain strategically relevant as diversification avenues and as channels where lightweight, cost-optimized configurations can gain traction. The strategic takeaway is that regional strategy must be calibrated to local compliance environments, labor dynamics, and the pace of workshop technology adoption rather than assumed through a uniform global template.
Competitive Architecture and Strategic Positioning
The competitive field is defined by a mix of established North American manufacturers, European engineering specialists, and broadening supply capabilities from Asia-based equipment groups. Each category brings a distinct strategic posture, product philosophy, and channel advantage that shapes market execution.
Among the most prominent incumbents, Hunter Engineering Company has reinforced its reputation through the integration of advanced diagnostic balancing with hands-off operational workflows. The introduction of the Road Force WalkAway wheel balancer, featuring an automatic hands-off inflation system, directly addresses one of the most persistent workshop bottlenecks: tire changeover time. By reducing four-tire changeover times by up to 45 percent, the solution exemplifies how automation can translate into measurable labor savings and throughput gains. Its demonstration at the SEMA Show 2025, paired with an integrated Revolution tire changer, signals a broader ecosystem strategy in which balancing equipment is increasingly positioned as part of coordinated service lines rather than isolated tools.
Coats Company LLC has carved out a strong footprint in heavy-duty and high-volume service environments. Its Direct Drive balancing platforms, including the HD-6450 and ProBalance E900 models, are engineered for durability, speed, and operational consistency in tire service operations where uptime and repeatability are paramount. The strategic value of such offerings lies in their alignment with commercial and high-throughput passenger service requirements, where equipment reliability directly affects shop scheduling and customer turnaround expectations.
Snap-on Incorporated continues to leverage its broad professional tool ecosystem by supplying motorized wheel balancers, including Sun Wheel Balancer lines and the EEWB334A model, tailored for high-volume shop use. The company's channel strength and brand trust within professional service networks provide a durable distribution advantage, particularly in markets where integrated tool procurement and service support are decisive purchasing criteria.
CEMB S.p.A. brings a European engineering perspective, emphasizing garage and truck-oriented balancing solutions with vibration analysis integration and touchless alignment compatibility. Its product direction reflects a growing convergence between balancing, alignment, and diagnostic inspection capabilities, a trend that is gaining relevance in facilities seeking to consolidate service functions and reduce equipment footprint.
IMI Products has pursued a highly targeted strategic path with the Equal FLEXX internal adaptive balancing system, designed specifically for fleet truck tires with an emphasis on vibration reduction and fuel efficiency improvements. The approval of this system by UPS for its 2026 Tire Solutions Program, following a two-year field evaluation exceeding 10,000 assemblies, illustrates the growing importance of fleet-validated performance in commercial segment decision-making. Such endorsements can materially influence procurement standards within large fleet operations and signal a shift toward evidence-based equipment selection.
Balance Group, operating from China, represents a broadening manufacturing presence that integrates wheel balancers into comprehensive tire service equipment lineups spanning car, motorcycle, truck, and heavy-duty wheels. This integrated equipment strategy enables suppliers to address broader service facility needs through bundled offerings, a model that can be especially compelling in growing markets where dealers and workshops favor consolidated procurement and after-sales support.
Beyond named incumbents, the competitive environment also reflects product innovation from other regional players. For example, the launch of new heavy-duty wheel balancer lines incorporating Tri-Sensor Technology and LCD displays underscores an ongoing industry-wide push toward improved precision, operator visibility, and workshop usability. Collectively, these developments highlight that competition is no longer defined solely by price or basic balancing capability; it is increasingly determined by workflow integration, automation readiness, fleet validation, and the ability to align equipment performance with compliance and efficiency mandates.
Wheel Balancer Market
Regulatory, Safety, and Operational Dynamics
The market does not operate in a regulatory vacuum. Equipment standards governed by OSHA, CE, and ISO frameworks shape workshop safety requirements for tire handling equipment, including wheel balancers, and influence procurement specifications across commercial and institutional buyers. Simultaneously, mandatory periodic technical inspection regimes, such as TÜV and MoT-aligned systems, reinforce the necessity of accurate wheel balancing as a component of vehicle safety compliance. These regulatory touchpoints create predictable, recurring demand drivers while also establishing performance expectations that newer or less-established entrants must meet to gain acceptance in professional service channels.
A parallel operational dynamic is the reduction of technician dependency through automated balancing cycles. As labor markets tighten and service facilities face pressure to maintain output with constrained staffing, automation functions that accelerate balancing procedures and reduce manual intervention are becoming central to equipment evaluation. This trend favors manufacturers that can demonstrate measurable cycle-time improvements, reduced re-work, and enhanced operator usability, while alsofavoring service providers who can translate equipment upgrades into service capacity expansion without proportionally increasing labor costs.
Strategic Implications for 2026 Enterprise Decision-Making
For executives evaluating market entry, portfolio expansion, partnership structures, or capital equipment procurement, the 2026 landscape presents several actionable imperatives. First, product strategy must account for the growing convergence of balancing, inflation automation, and diagnostic integration. Solutions that streamline tire service workflows and reduce changeover friction are gaining preferential positioning in high-volume and fleet-adjacent environments. Second, procurement and channel strategy should be calibrated to regional compliance expectations and labor economics, recognizing that the same equipment may deliver different value propositions depending on inspection regimes, workshop staffing models, and customer throughput requirements. Third, commercial vehicle and fleet-oriented segments reward evidence-based validation and long-term reliability, making field-proven performance and fleet endorsements increasingly influential in enterprise purchasing decisions.
Supply-side positioning also requires disciplined attention to concentration dynamics and differentiation pathways. In a market where leading players hold a meaningful share of revenue, new entrants and expanding manufacturers must identify defensible niches; whether through heavy-duty specialization, adaptive internal balancing, integrated service equipment bundling, or automation-enabled speed gains. Pricing competition alone is unlikely to sustain long-term advantage; rather, value capture will accrue to those who can align equipment performance with the operational realities of modern tire service facilities.
Why This Market Research Delivers Strategic Value
This study is designed to move beyond surface-level sizing and into the operational, competitive, and regulatory mechanics that actually shape procurement behavior and product strategy. The report integrates historical performance data, forward-looking growth architecture, and segmentation-level strategic interpretation, while protecting sensitive quantitative detail for clients who require granular intelligence for investment modeling and market planning. It examines equipment type dynamics, application-specific demand profiles, and regional deployment considerations with an emphasis on how these variables translate into pricing behavior, channel strategy, and differentiation opportunity.
Equally important, the analysis embeds competitive profiling and recent market developments into a cohesive strategic narrative. Product launches, trade show demonstrations, fleet approvals, and regulatory-driven operational shifts are evaluated not as isolated events, but as indicators of where industry momentum is heading and which capabilities are becoming table stakes. This contextual depth enables executives to anticipate demand shifts, benchmark competitive positioning, and align internal roadmaps with the structural forces that will define the 2026 to 2032 period.
Accessing the Full Intelligence Framework
The macro trajectory, segmentation architecture, concentration profile, and competitive developments outlined here represent a strategic preview of the full research. Detailed quantitative breakdowns, scenario analysis, supplier benchmarking, and region-specific deployment insights are reserved for the complete report. For organizations seeking to make informed equipment procurement, market entry, or product strategy decisions in the Wheel Balancer Market, the full study provides the structured intelligence necessary to convert industry momentum into actionable advantage.
The market is advancing with measurable consistency and increasing technological differentiation. In that environment, the most resilient strategies will be those built on precise understanding of demand drivers, regulatory reinforcement, automation economics, and competitive capability. This research is purpose-built to supply that understanding, enabling decision-makers to navigate the next phase of market evolution with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Wheel Balancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fuel Cell Electric Vehicles Market to Surge at 26.6% CAGR, Hit $37M by 2032
By pmarketresearch, 2026-09-15
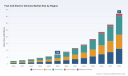
Strategic Intelligence for the Hydrogen Horizon: Navigating the 2026 Fuel Cell Electric Vehicle Landscape
Executive Summary: The Inflection Point of Hydrogen Mobility
The global transition toward sustainable transportation has entered a decisive phase. While battery electric vehicles have dominated early headlines, the Fuel Cell Electric Vehicle (FCEV) market is now demonstrating a distinct and robust growth trajectory, particularly in sectors where energy density and refueling speed are critical. As we move through 2026, industry leaders are shifting from pilot programs to scale-up strategies, driven by tightening decarbonization regulations and advancements in hydrogen infrastructure.
Electric Vehicles and Fuel Cell Vehicles Market
PW Consulting presents this comprehensive market research insight to equip stakeholders with the clarity needed to navigate this evolving landscape. Our analysis covers the period from 2020 through 2032, providing a detailed view of historical performance and future projections. The market, valued at approximately 2.21 billion USD in 2020, has seen accelerating momentum, reaching an estimated 7.08 billion USD by the base year of 2025. This trajectory underscores a compound annual growth rate (CAGR) of 26.6 percent throughout the forecast period extending to 2032. For corporate strategists, investors, and policy advisors, understanding the drivers behind this expansion is not merely an academic exercise but a requisite for capital allocation and product roadmap planning.
This article serves as a high-level overview of the strategic intelligence contained within our full report. It highlights the macroeconomic momentum, competitive dynamics, and regulatory pressures shaping the industry. However, the precise segmentation data, granular regional revenue splits, and specific application-level forecasts are reserved for the complete study. These detailed intelligence assets are critical for precise market entry strategies and are available through our comprehensive dataset.
Market Trajectory: From Niche Technology to Mainstream Adoption
The historical data from 2020 to 2025 reveals a consistent upward curve in market valuation. Starting at 2.21 billion USD, the market grew to 2.78 billion USD in 2021 and 3.46 billion USD in 2022. This growth accelerated through the pandemic recovery period, reaching 4.48 billion USD in 2023 and 5.61 billion USD in 2024. By 2025, the market revenue unit crossed the 7 billion USD threshold, signaling a maturation of the technology stack and supply chain.
Looking ahead, the forecast period from 2026 to 2032 projects aggressive expansion. The market size is anticipated to reach 9.06 billion USD in 2026, climbing to 11.69 billion USD in 2027 and 14.29 billion USD in 2028. By the end of the decade, valuations are expected to approach 23.59 billion USD in 2030, culminating at 37.0 billion USD by 2032. This momentum suggests that FCEVs are transitioning from early adoption to a growth phase driven by commercial viability. The double-digit CAGR indicates that investment flows into hydrogen technology are yielding tangible market returns, though the pace varies significantly by vehicle type and region.
Stakeholders analyzing this growth curve must consider the underlying volume drivers. The revenue growth is not uniform across all vehicle categories. Our deep-dive analysis examines how passenger cars compare against commercial heavy-duty trucks and vans in terms of revenue contribution and unit sales. While specific percentage splits are detailed in the full report, it is clear that commercial applications are generating substantial revenue due to higher unit values and intensive usage patterns. Understanding the balance between passenger and commercial segments is vital for manufacturers deciding where to allocate engineering resources and production capacity in 2026 and beyond.
Competitive Landscape: Key Players and Strategic Maneuvers
The FCEV market is characterized by a mix of automotive giants and specialized technology providers. Market concentration data indicates that the top three players hold a combined market share of 48.0 percent, while the top five control 52.0 percent of the market. This moderate concentration suggests a competitive environment where established leaders must defend their position against emerging challengers and new entrants leveraging patent portfolios or regional advantages. The following key companies are central to the current dynamics:
- Toyota Motor Corporation (Toyota City, Japan) : A pioneer in hydrogen mobility, Toyota continues to push the boundaries of passenger FCEV technology. Their flagship Mirai model integrates advanced fuel cell systems designed for performance and durability. The company's strategy focuses on maintaining technological leadership while expanding partnerships for hydrogen supply chains.
- Hyundai Motor Company (Seoul, South Korea) : Hyundai has aggressively positioned itself in both passenger and heavy-duty segments. With the Nexo passenger vehicle and the Xcient heavy-duty truck, Hyundai addresses diverse use cases. Their recent product debuts highlight a commitment to continuous innovation, leveraging over two decades of FCEV development experience.
- Honda Motor Co., Ltd. (Tokyo, Japan) : Honda complements its passenger offering with the CR-V e:FCEV, which combines fuel cell technology with plug-in battery capabilities. This hybridization strategy aims to maximize flexibility for users. Additionally, Honda supplies fuel cell systems for commercial applications, diversifying its revenue streams beyond vehicle sales.
- BMW Group (Munich, Germany) : Entering the fray with a focus on series production, BMW is targeting market entry around 2028. Their development programs emphasize integrating fuel cell technology into existing platforms while ensuring cost competitiveness. BMW's entry signals growing confidence in the long-term viability of hydrogen for premium automotive segments.
Recent developments during 2025 illustrate the active pace of product launches and strategic announcements. In July 2025, Honda began customer leasing of the CR-V e:FCEV in California, utilizing U.S.-made fuel cell modules. This move demonstrates a shift toward localized production and reduced logistical barriers. In November 2025, Hyundai debuted the all-new NEXO at the Japan Mobility Show, previewing a production model that reinforces their leadership in the passenger segment. Furthermore, the California Air Resources Board released its 2025 Annual Evaluation in December 2025, reporting 14,128 FCEVs registered in California as of April 2025. This data point provides a critical benchmark for regional adoption rates, though a slight year-over-year decline of 291 units highlights the volatility and challenges inherent in scaling infrastructure-dependent technologies.
These corporate actions and regulatory reports are interconnected. For instance, the CARB projection of a maximum of 112 stations enabling up to 16,210 FCEVs by 2028 creates a tangible ceiling for growth in key markets unless infrastructure investment accelerates. Companies are responding by aligning product launches with infrastructure milestones. Our full report analyzes how these timing mismatches between vehicle availability and fueling networks impact market penetration rates and what strategies firms are employing to mitigate risk.
Regulatory and Infrastructure Dynamics: The Dual Engines of Growth
The FCEV market does not exist in a vacuum. It is heavily influenced by policy frameworks and infrastructure readiness. The regulatory environment, particularly in regions with aggressive decarbonization targets, acts as a powerful catalyst. The Fuel Cell and Hydrogen Energy Association (FCHEA) highlighted these dynamics during the 2025 Hydrogen & Fuel Cell Seminar, emphasizing that policy alignment is driving commercialization in heavy-duty sectors. This suggests that while passenger vehicles often garner media attention, the commercial and heavy-duty segments may offer faster pathways to regulatory compliance and economic scale.
Infrastructure remains the critical bottleneck. The CARB 2025 Annual Evaluation underscores the need for hydrogen fueling station network expansion. With the projection of 112 stations supporting a specific capacity by 2028, the gap between current station counts and required coverage is evident. Strategic planners must evaluate not just the total number of stations, but their geographic distribution and reliability. Market participants are increasingly looking at public-private partnerships and government incentives to bridge this gap. Our analysis explores the correlation between station density and vehicle registration rates, revealing insights that are essential for infrastructure investors and fleet operators planning hydrogen procurement strategies.
Moreover, the industry context includes noise from various regulatory signals. Reports indicate that the first recorded decline in FCEV registrations in California, with 14,128 units as of April 2025, serves as a cautionary signal. This decline may reflect temporary factors such as supply chain constraints, vehicle model turnover, or consumer hesitation due to infrastructure anxiety. Understanding the root causes of such fluctuations is key to distinguishing between cyclical noise and structural shifts. The full market research delves into these nuances, providing context for interpreting raw registration data against broader economic and technological trends.
Strategic Implications for 2026 Decision Makers
For executives and analysts operating in 2026, the FCEV market offers both opportunity and complexity. The expansion from 9.06 billion USD in 2026 to over 37.0 billion USD by 2032 represents a significant addressable market. However, capturing value within this growth requires precise execution. Decision makers must balance investments across vehicle types, considering the differing total cost of ownership profiles for passenger versus commercial applications. They must also navigate the competitive landscape where market leaders hold substantial shares but face pressure from new technological iterations and regional players.
Fuel Cell Electric Vehicles Market
Strategic questions that this market research helps answer include: Which vehicle segments offer the highest margin potential in the current regulatory environment? How do geopolitical factors and hydrogen production costs influence regional market attractiveness? What are the timing implications of competitor product launches on market share erosion? While we have outlined the broad strokes of market size and key players here, the specific regional revenue contributions and detailed application breakdowns are provided in our complete study. These details allow for scenario planning and risk assessment that high-level summaries cannot support.
Additionally, the interaction between policy and technology adoption requires continuous monitoring. The FCHEA seminar discussions and CARB reports indicate a dynamic regulatory environment where targets are being set and adjusted based on deployment realities. Companies that can anticipate regulatory shifts and align their product pipelines accordingly will gain a first-mover advantage. Our report includes a timeline of regulatory milestones and policy announcements, helping organizations stay ahead of compliance requirements and incentive programs.
Conclusion and Access to Full Intelligence
The Fuel Cell Electric Vehicle market is at a pivot point. Historical growth from 2020 to 2025 has established a foundation, and the forecast through 2032 points to a transformative decade for hydrogen mobility. The involvement of major automakers like Toyota, Hyundai, Honda, and BMW, combined with active regulatory bodies and industry associations, creates a vibrant ecosystem of innovation and competition. Yet, the path to widespread adoption is fraught with infrastructure challenges and competitive intensity.
PW Consulting's full Fuel Cell Electric Vehicles Market research report offers a deeper layer of analysis required for sophisticated strategic planning. We provide granular segmentation data, including specific regional revenue estimates and application-level breakdowns, which are essential for market entry analysis and competitive benchmarking. Our proprietary datasets cover the sales volume trends, price dynamics, and supply chain vulnerabilities that influence profitability. We also offer comprehensive profiles of key suppliers and technology developers, along with an assessment of the risk factors that could alter the growth trajectory.
To access the complete set of market size projections, competitive intelligence, and actionable recommendations, we invite you to explore the full report. In an environment where data precision can determine investment success, our detailed insights provide the clarity needed to make informed decisions in the rapidly evolving FCEV sector.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whole-house Ventilation System Market to Hit $5.97B by 2032 at 6.52% CAGR
By pmarketresearch, 2026-09-15
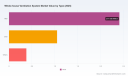
Strategic Horizons in Whole-House Ventilation: Navigating the 2026 Market Landscape
The global transition toward healthier, more energy-efficient living spaces has moved whole-house ventilation systems from a niche building specification to a central pillar of modern residential and commercial infrastructure. As building codes tighten, urban air quality concerns intensify, and consumers grow increasingly aware of the link between indoor environments and human wellness, the market is undergoing a structural recalibration. Our latest research report, Whole-house Ventilation System Market, offers a comprehensive, data-grounded assessment of how this sector will evolve from 2026 through 2032. This article serves as an executive preview, outlining the strategic rationale behind the study and why decision-makers across manufacturing, distribution, construction, and investment should treat the findings as a critical input for 2026 planning.
Residential Ventilation Systems Market
The Macro Trajectory: A Market Accelerating on Multiple Fronts
Tracking the sector over a twenty-five-year window reveals a clean upward arc. Revenue climbed from a modest 2.8 billion USD in 2020 to an estimated 3.84 billion USD in 2025, reflecting sustained demand for balanced air exchange solutions that simultaneously manage indoor humidity, dilute airborne contaminants, and reduce the energy penalty traditionally associated with bringing in outdoor air. Looking ahead, the forecast period paints a picture of consistent expansion. By the close of 2026, total revenue is projected to cross the 4 billion USD threshold, continuing upward through the early and mid-2030s before reaching approximately 5.97 billion USD by 2032. The compound annual growth rate sits at 6.52 percent, a figure that underscores the market's resilience and its capacity to compound value at a rate that outpaces several adjacent building-system categories.
For executives evaluating capital allocation, channel investment, or product-line prioritization, this trajectory carries immediate implications. A 6.52 percent CAGR signals a sector that is neither saturating nor speculative; rather, it is approaching the phase where adoption curves steepen as code requirements spread, retrofit pipelines mature, and energy-recovery pairings become standard rather than optional. Our study isolates the structural drivers behind this growth and maps them against realistic capacity expansion timelines, regional deployment patterns, and the shifting economics of installation labor and component sourcing. The purpose is not to simply confirm that the market is growing, but to clarify where the growth concentrates, which demand vectors will pull hardest, and how to align operational strategy ahead of the next wave of policy and consumer momentum.
Regulatory Catalysts and the Changing Compliance Environment
Technology adoption in the built environment rarely advances on product performance alone. It is frequently accelerated by code updates, commissioning standards, and liability frameworks that reshape the cost-benefit calculus for specifiers and contractors. In 2026, whole-house ventilation operates inside a noticeably more demanding regulatory perimeter. The 2025 California Energy Code prohibits exhaust-only systems in new multifamily construction and requires fault indicator displays for HRV/ERV installations, effectively pushing projects toward balanced, diagnosable solutions that can demonstrate performance over time. Complementary guidance from the California Energy Commission has introduced the NRCA-MCH-23-A acceptance test, which verifies airflow delivery, sensible recovery capacity, and fan-power compliance for multifamily applications, establishing a practical benchmark for installation quality.
Meanwhile, ASHRAE Standard 62.2 continues to anchor minimum ventilation rate requirements across countless residential codes, providing a consistent technical reference for designers who must balance indoor air quality targets against energy budgets. According to data from the Home Ventilating Institute, roughly half of U.S. jurisdictions now require whole-house ventilation as a feature in new single-family and multifamily homes through their current building code adoptions. These dynamics do not merely increase baseline demand; they alter the competitive logic of the sector by rewarding manufacturers and integrators that can deliver documented performance, field-serviceable diagnostics, and system configurations that satisfy both code officials and end users. Our analysis examines how these regulatory shifts redistribute opportunity across product configurations, installation models, and value propositions, while deliberately leaving the exact regional percentages and segmented revenue allocations for the full report.
Competitive Architecture: A Fragmented Landscape with Clear Differentiation
The competitive field is broad, and it rewards firms that can align product engineering with installation realities, regional climate profiles, and the specific certification expectations of their target markets. Carrier remains a prominent presence through its energy-efficient HRV and ERV ventilator systems, which emphasize whole-house indoor air quality and balanced ventilation in both new construction and retrofit contexts. Zehnder America supports a similar mission with its ComfoAir series of ERV and HRV units, designed to deliver high-efficiency fresh air supply across whole-house residential applications. Panasonic extends its North American footprint with the WhisperComfort ERV and related heat/recovery ventilator systems, focusing on residential-scale deployment where noise control and integration simplicity matter. Broan-NuTone offers an integrated portfolio that includes ERV and HRV options for whole-house fresh air exchange, often positioned for builders seeking a single vendor relationship across multiple indoor environmental products.
RenewAire contributes a balanced ERV approach engineered specifically for residential indoor air quality, while Lifebreath stands out for cold-climate ERV and HRV systems optimized to preserve whole-house ventilation performance in demanding winter conditions. EXINDA channels its North American operations toward HVI-certified ERV units that meet regional compliance expectations for whole-house fresh air solutions, appealing to specifiers who value third-party verification. Trane integrates whole-house ventilation into broader HVAC offerings, aiming to improve indoor air quality and balance air exchange across residential installations. STIEBEL ELTRON brings central ventilation systems with enthalpy heat exchangers, structured around whole-house indoor air quality and energy-conscious heat recovery. Aereco differentiates with hybrid ventilation systems that apply room-by-room demand control to whole-house residential use, aligning airflow delivery more closely with occupancy and conditions.
The broader competitive pattern is clear: consolidation is not eliminating differentiation, but rather sharpening it. Market concentration remains moderate, with the top three and top five groups holding meaningful but not overwhelming shares, leaving room for regional specialists, performance leaders, and integrators that can solve the full problem of installability, commissioning, and customer education. Our report examines the positioning strategies, product signals, and partnership behaviors that distinguish these participants without disclosing the specific market-share figures reserved for the full dataset.
What the Study Contains: Actionable Intelligence, Not Just Narrative
This market study is built for practitioners who need to translate market signals into operating decisions. The report begins with a rigorous historical reconstruction of revenue performance across the base period, then extends into a forward view that aligns 2026 through 2032 forecasts with the structural conditions shaping demand. Rather than presenting a single aggregate number, the analysis decomposes the market along the dimensions that matter most to strategy: technology distinctions, application contexts, and geographic patterns. That segmentation is paired with practical evaluations of purchasing behavior, specification drivers, installer readiness, and the relative attractiveness of new-build versus retrofit pathways.
Beyond segmentation, the study delivers meaningful competitive coverage. It profiles the companies shaping the category, including their home bases, public-facing product directions, and the specific ventilation approaches they emphasize for whole-house indoor air quality and balanced air exchange. The competitive review supports a range of practical decisions, from channel partnership design to product roadmap prioritization and M&A scouting. The study also addresses the dynamics that will influence profitability and execution risk, including the cost environment for recovery media, fan-motor efficiency, control integration, and the labor skills required to install and commission balanced systems at scale. The intent is to help readers understand where margin pressure is likely to emerge, where differentiation can protect pricing, and how regulatory momentum could change the speed of adoption in different project environments.
To keep the analysis grounded, the report ties market mechanics to the surrounding ecosystem: the standards that define acceptable performance, the code provisions that establish minimum ventilation expectations, and the acceptance-test practices that increasingly influence whether a system is judged successful in the field. By connecting these elements, the study turns market data into decision utility. It helps leaders answer questions such as where to focus engineering investment, which applications are most likely to support accelerated growth, how to plan distributor and contractor support, and what evidence is needed to defend forecasts in front of internal stakeholders or external partners.
Why This Research Matters for 2026 Decision-Making
Executives entering 2026 face a market that is large enough to matter, fast enough to require urgency, and complex enough to reward precision. The growth trajectory is strong, but the value does not accrue uniformly. Companies that treat the sector as a generic HVAC adjacency risk misjudging where specification momentum is strongest, which customer segments will convert fastest, and which compliance requirements will become table stakes rather than differentiators. The report is designed to reduce that uncertainty. It gives leadership teams a defensible map of the market’s shape, a clear sense of the forces accelerating adoption, and a structured view of the competitive behaviors that will define winning positions over the forecast horizon.
The study is particularly relevant for organizations deciding how to allocate resources across product development, go-to-market design, and compliance readiness. If a manufacturer is assessing whether to deepen its HRV lineup, expand ERV capacity, or strengthen hybrid and demand-control offerings, the analysis provides the context needed to weigh technical differentiation against market pull. If a distributor or building science consultancy is determining where to invest sales coverage, training, and commissioning support, the report highlights the application and code dynamics that shape installation volumes and project lead times. For investors, the report offers a foundation for evaluating the durability of growth assumptions and the competitive defensibility of participating firms, again without exposing the granular quantitative blocks that sit in the full document.
Reading the Signals, Not Just the Scale
The most valuable insight in a market study is not the headline size, but the logic behind it. The whole-house ventilation category is expanding because it is solving a set of interconnected problems: indoor air quality, humidity management, energy recovery, code compliance, and occupant comfort. Each of those problems carries its own adoption drivers, its own technical constraints, and its own economic implications. Our research reflects that complexity and translates it into a structured view that leaders can use when they are planning product roadmaps, sales coverage, service readiness, and partnership strategy. The 6.52 percent growth path is a useful signal, but the strategic power comes from understanding what will steepen or soften that curve, where the concentration of opportunity sits, and how competitors are likely to respond as code requirements deepen and specifier expectations rise.
The full report is intended for readers who want more than directional confidence. It delivers the detailed segmentation, the granular forecast architecture, and the competitive intelligence needed to convert a strong market narrative into a concrete 2026 plan. For leadership teams weighing market entry, capacity expansion, channel investment, or technology focus, the study offers the evidence base to make those calls with greater precision. The invitation is straightforward: use this preview to understand the strategic landscape, then secure the complete intelligence to pressure-test assumptions, calibrate targets, and align execution before the next cycle of code adoption, regional demand shifts, and competitive repositioning unfolds.
Whole-house Ventilation System Market
For detailed analysis of this topic, please visit the official page: Whole-house Ventilation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Relay Market Hits $17.85B in 2025, Projected to Reach $26.71B by 2032 at 6.2% CAGR
By pmarketresearch, 2026-09-15
Navigating the Automotive Relay Market: Strategic Intelligence for 2026 Decision-Makers
The automotive sector stands at a critical inflection point where electrification, lighter materials, and smarter architectures are reshaping every component value chain. Among the seemingly mundane yet operationally essential parts, relays remain indispensable. They bridge control logic and high-current execution, enabling everything from powertrain actuation to safety-critical load switching. For executives planning capital allocation, sourcing strategies, or product roadmaps in 2026, understanding the trajectory of the automotive relay market is not an academic exercise. It is a prerequisite for resilient, cost-aware growth. This article previews the strategic architecture of our latest Automotive Relay Market research and explains why its full intelligence is essential for confident decision-making this year.
The Macro Trajectory: A Market in Sustained Expansion
Drawing on a comprehensive historical baseline spanning 2020 through 2025 and extending across a seven-year forecast window to 2032, the automotive relay sector demonstrates consistent upward momentum. From a base measuring above thirteen thousand million USD, the market has advanced through successive annual increments, surpassing seventeen thousand million USD by 2025 and crossing the eighteen thousand million million milestone in 2026. The trajectory reflects compounding annual growth, driven by vehicle electrification, increased electrical content per platform, and the proliferation of high-current switching requirements in next-generation architectures. Rather than a single-sector surge, the expansion is broad-based: multiple on-road and off-road applications, varied regional manufacturing footprints, and diverse relay form factors are contributing to an aggregate image that rewards strategic clarity over reactive purchasing.
Time Delay Relays Market
Forecast Horizons and Strategic Planning Utility
The forecast period stretches to 2032, giving planning teams a long enough runway to evaluate CAPEX cycles, supplier qualification windows, and platform refresh timelines. The extended horizon is particularly valuable because relay selection is rarely a short-term procurement decision. It embeds into vehicle architecture, service interval planning, and regional compliance pathways. Our research translates this extended time frame into actionable planning matrices, enabling leadership to align sourcing commitments with product lifecycle cadence rather than reacting to spot-market volatility. The full report contains the granular year-by-year projections and scenario layers that allow teams to stress-test assumptions against shifting input costs, regional demand shifts, and competitive pressure.
Growth Catalysts Embedded in System Architecture
The driving force behind the expansion is not isolated to one application category. It is the cumulative effect of higher electrical loads, tighter packaging constraints, and the transition toward architectures that demand compact, high-reliability switching devices. As vehicle platforms evolve, relay specifications are becoming more demanding in terms of current handling, thermal resilience, and miniaturization. Simultaneously, cost discipline remains paramount, creating a tension between performance requirements and unit economics. Our study unpacks where these dynamics intensify, where they moderate, and how they influence total cost of ownership across the value chain. Rather than offering a single read on demand, the report segments the picture so that engineering, procurement, and strategy teams can align on the specific drivers relevant to their product families and target segments.
Segmentation Depth: Reading the Market Beyond the Aggregate
An aggregated headline number is useful for executive briefings, but it is insufficient for operational decision-making. The real value lies in understanding how the market behaves across technology types, application areas, and regional footprints. Our research provides a structured view that lets organizations isolate the demand pools most relevant to their capabilities and ambitions, while remaining mindful of competitive saturation and differentiation opportunities.
Technology Form Factors: Matching Performance to Platform Needs
Relays in modern vehicles are not a uniform product class. The market encompasses printed-circuit-board-mounted relays, plug-in variants, high-voltage solutions, and an additional set of application-specific offerings. Each family serves distinct design constraints and system requirements. PCB-mounted devices align with compact control modules and high-density electronics packaging. Plug-in relays support modular assembly and serviceability in discrete sub-systems. High-voltage categories respond to the shifting load profiles associated with electrification, where switching capability, arc management, and insulation integrity become critical selection criteria. By separating demand across these types, the report helps engineering and sourcing teams evaluate where to invest in qualification, where to consolidate spend, and where to expect price and availability pressure. The full dataset reveals the precise allocation across categories, enabling precise SKU rationalization and supplier negotiation leverage that an aggregated summary cannot provide.
Application Mapping: Where the Demand Actually Resides
From a demand perspective, relays feed into multiple vehicle domains: powertrain systems, body and chassis functions, safety and security subsystems, HVAC and comfort components, and EV battery management functions. Each application carries different performance expectations, volume profiles, and qualification rigor. Powertrain-related switching tends to emphasize durability, current capacity, and thermal resilience. Body and chassis applications often prioritize cost efficiency and integration flexibility. Safety and security functions introduce stricter reliability thresholds and traceability expectations. Comfort and climate systems blend volume scale with moderate performance requirements. EV battery management represents a specialized, fast-evolving domain where switching reliability and voltage handling are paramount. Our segmentation view maps these demand streams so leadership can avoid over-indexing on one vertical while underestimating growth in another. The complete report contains the detailed split that supports portfolio prioritization and resource allocation decisions.
Regional Distribution: Planning Around Localized Demand and Supply
Geography shapes both demand and competitive dynamics. Different regions present distinct vehicle production volumes, regulatory environments, cost structures, and supplier maturity. North American, European, and Asia Pacific markets each contribute meaningfully to total demand, while Latin America and the Middle East and Africa represent additional, often specialized, demand pockets. A regional lens is essential for capacity planning, logistics design, and competitive positioning, particularly when raw material pricing, local content expectations, and certification pathways vary by market. Our research outlines the regional demand structure so organizations can decide where to locate inventory, which suppliers to qualify, and how to hedge against regional supply disruptions. The full report's regional breakdown enables precision in regional strategy without disclosing the exact allocation figures that competitors could exploit if presented in isolation.
Competitive Landscape and Strategic Positioning
The automotive relay market is not dominated by a single winner-takes-all player. Competitive concentration is moderate, which means differentiation, supply chain reliability, and technological readiness still create room for advantage. Our research profiles a broad set of global and regional participants, helping teams understand who competes on performance, who competes on cost, and who competes on integration depth with vehicle manufacturers and Tier 1 suppliers.
Automotive Relay Market
The competitive field includes established multinational firms and capable regional manufacturers. Profiles cover companies such as TE Connectivity, Omron Corporation, Panasonic Corporation, Siemens AG, Phoenix Contact, Schneider Electric, Finder, Cit Relay & Switch, HKE, Xiamen Hongfa Electroacoustic Co., Ltd., Forward Relay, Huaguan, Shenler, Denso Corporation, Robert Bosch GmbH, Eaton Corporation, and Fujitsu Component Limited. These organizations participate across different segments and regions, and their strategic postures diverge based on product breadth, voltage-class readiness, packaging expertise, and proximity to vehicle programs. Rather than treating the landscape as a static list, the report maps how these players are positioned relative to one another in terms of addressable demand, technology emphasis, and regional strength. This framing helps procurement teams benchmark supplier options and helps product teams identify white space for differentiated offerings. The full report delivers the deeper competitive assessment, including positioning nuances that inform partnership selection, negotiation strategy, and risk diversification.
Market Dynamics: Cost Pressure, Innovation, and Regulatory Signals
Market growth does not occur in a vacuum. Cost structures, product launches, and regulatory or compliance considerations all shape the pace and shape of demand. Our research incorporates the dynamic factors that should influence 2026 planning, particularly for teams evaluating supplier stability, margin resilience, and technology roadmaps.
Raw Material and Component Cost Signals
Input cost volatility remains a strategic concern. Recent supplier notices point to material and component price adjustments that can affect relay and associated electromechanical product economics. For example, one major electrical equipment manufacturer announced bulk commodity price-driven increases of up to 40 percent on certain contactor and relay series and related accessories, effective in March 2026. Separately, a major industrial manufacturer announced price increases in the range of 30 percent for glass epoxy multi-layer circuit board materials and 20 percent for prepreg used in relay and electronic component production, effective in April 2026. These developments underscore the importance of forward-looking cost modeling, dual-sourcing strategies, and design-for-cost initiatives. Our study places these signals in context so organizations can anticipate where cost pass-through pressure may emerge and where value engineering can protect margins.
Product Launches That Reshape Performance Expectations
Innovation in the relay category is moving toward higher voltage handling, bidirectional switching, compactness, and improved sustainability profiles. In April 2025, Omron Corporation introduced the G9EK High-Voltage DC Relay, a compact 500 VDC 120 A bidirectional gasless relay designed for next-generation EV charging, battery systems, and power electronics, with carbon neutrality attributes enabled by a gasless plunger-type design that supports 500 VDC 120 A bidirectional switching without gas filling. Around the same period, Durakool introduced the DG86M high-current automotive relay featuring magnetic arc blowout technology for industrial vehicle electrification, delivering 150 A at 72 VDC and 25 A at 250 VDC in a compact lightweight design, with engineering targeted at 15,000 operations with integrated resistor and 5,000 operations with integrated diode. These launches demonstrate that the category is evolving from basic switching toward application-tuned, high-performance solutions. The report translates such developments into implications for design requirements, supplier evaluation, and portfolio planning, while withholding the full competitive benchmarking detail until readers access the complete study.
Regulatory and Sustainability Considerations
Beyond immediate product specifications, sustainability expectations and compliance considerations are increasingly influencing component selection. Gasless design approaches, material efficiency, and lifecycle considerations are becoming part of technical evaluations, especially for programs with stringent environmental targets. At the same time, regulatory expectations around vehicle safety, electrical protection, and component qualification continue to shape acceptance criteria. Our research integrates these considerations into the market dynamics section, helping teams understand where sustainability attributes influence purchase decisions and how compliance burdens differ across applications and regions. The complete report expands on these dynamics with structured analysis that can be aligned to internal sustainability goals and program requirements.
What the Full Report Delivers for 2026 Decision-Making
This preview has outlined the strategic shape of the market: sustained growth, diversified demand across types and applications, a moderately concentrated competitive field, and a backdrop of cost pressure and product innovation. Yet the difference between broad awareness and competitive advantage lies in the specifics. The complete Automotive Relay Market research is built to give decision-makers the precision required to act with confidence.
Inside the full report, readers will find detailed market sizing across the historical and forecast periods, enabling year-by-year resource planning and scenario comparison. The segmentation analysis breaks down demand by technology type, application, and region with sufficient granularity to support SKU strategy, supplier selection, and regional capacity planning. Competitive profiles provide structured insight into the positioning, scope, and strategic emphasis of key players, allowing teams to benchmark their own offering and identify partnership or procurement targets. Market dynamics coverage brings together cost signals, innovation milestones, and regulatory context into a coherent view that supports both short-term sourcing decisions and long-term portfolio planning.
Equally important, the report is organized for practical use rather than passive reading. It is structured to support multiple internal audiences: strategy teams evaluating market entry or expansion, procurement teams managing supplier risk and cost, engineering groups selecting relay specifications for new platforms, and finance teams modeling cost trajectories and margin exposure. By consolidating the analytical layers into one integrated view, the report reduces the time required to align cross-functional stakeholders around a shared market thesis.
For 2026, when planning cycles are increasingly sensitive to input cost variability, electrification-driven specification shifts, and regional supply chain considerations, strategic clarity is a direct enabler of execution quality. Our research is designed to provide that clarity while preserving the competitive sensitivity of the underlying detail. To explore the full segmentation, competitive positioning, and dynamic analysis that underpin this outlook, we invite you to access the complete market study. The detailed intelligence inside will help your organization move from general market awareness to informed, actionable strategy.
Why This Research Matters Now
The automotive relay market is expanding, evolving, and being contested by a diverse group of global and regional players. That combination creates both opportunity and risk. Organizations that understand where demand is concentrated, how technology types differ in value and cost behavior, and which competitive forces are intensifying will be better positioned to protect margins, secure supply, and align product development with real market pull. Those that rely on surface-level summaries risk overcommitting to the wrong segments, underestimating cost pressure, or missing the product innovations that are redefining performance expectations.
Our latest Automotive Relay Market research exists to close that gap. It translates a complex, multi-dimensional market into a structured intelligence asset that supports concrete 2026 decisions. The preview above establishes the professional depth of the analysis and the practical orientation of the content; the complete report delivers the data, segmentation, and competitive assessment needed to turn insight into action. We encourage leadership teams, sourcing professionals, and engineering strategists to review the full study and integrate its findings into their planning cycles this year.
For detailed analysis of this topic, please visit the official page: Automotive Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Thionyl Chloride Market Hits $679.8M in 2025, Growth at 4.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Thionyl Chloride Market Outlook 2026: Strategic Intelligence for Chemical and Battery Sector Decision-Makers
Executive Overview: Why This Market Intelligence Matters Now
The Thionyl Chloride Market is entering a decisive inflection point. As industrial demand matures alongside regulatory realignments in key manufacturing economies, companies that navigate this landscape with precise, forward-looking intelligence will secure measurable competitive advantage. PW Consulting's latest Thionyl Chloride Market report delivers exactly that: a rigorously structured, data-grounded assessment designed to convert macroeconomic signals into actionable corporate strategy.
This research is built for executives, procurement leaders, R&D directors, and investment analysts who require more than headline figures. The analysis spans a comprehensive historical baseline from 2020 through 2025, establishes a clear 2026 starting position, and projects market trajectories through 2032. By anchoring forecasts in verifiable historical growth patterns and structural industry shifts, the report equips stakeholders with the analytical confidence required to allocate capital, adjust supply chains, and position product portfolios ahead of market-wide transitions.
The strategic value of this publication lies in its dual focus: it captures the scale and tempo of market expansion while dissecting the operational, regulatory, and competitive forces that will shape enterprise outcomes year by year. Rather than presenting static snapshots, the research maps the causal relationships between feedstock dynamics, grade-level demand shifts, regional manufacturing realities, and the evolving battery and specialty chemical ecosystems that drive Thionyl Chloride consumption. For decision-makers operating in 2026, that contextual depth is not optional, it is foundational.
Market Trajectory and Structural Growth Signals
Historical Performance and Forecast Architecture
The Thionyl Chloride Market has demonstrated consistent, structurally supported expansion over the past half-decade. Historical revenue progression from 2020 to 2025 reflects a market that has moved beyond cyclical volatility into a phase of steady, demand-led growth. Building on that foundation, the forecast architecture projects a sustained upward trajectory through 2032, underpinned by a compound annual growth rate of 4.8 percent. This growth rate is not an abstract metric; it emerges from the convergence of enduring industrial applications, specialty chemical synthesis requirements, and the expanding role of Thionyl Chloride as a critical component in long-life battery chemistries.
Revenue progression across the forecast window reveals a market that compounds methodically rather than abruptly. The 2026 baseline establishes a clear reference point for near-term planning, while subsequent annual projections illustrate how cumulative demand, capacity adjustments, and application diversification will reshape total market value over the forecast horizon. For enterprise strategists, this phased visibility enables scenario modeling that aligns procurement cycles, production scheduling, and inventory planning with realistic market pacing rather than speculative spikes.
Demand Drivers and Application Resilience
The durability of Thionyl Chloride demand is rooted in its functional indispensability across multiple high-value sectors. As a chlorinating agent and synthetic intermediate, it remains embedded in pharmaceutical manufacturing, agrochemical formulation, organic synthesis, dyes and pigments production, and broader specialty chemical value chains. Equally significant is its role in battery applications, where Thionyl Chloride serves as a core electrolyte component for lithium thionyl chloride systems engineered for long service life, stable discharge performance, and demanding operational environments.
These application pillars do not grow in isolation. Pharmaceutical and agrochemical demand is shaped by regulatory compliance requirements, active ingredient complexity, and regional manufacturing footprints. Organic synthesis and specialty chemical pathways reflect the ongoing shift toward higher-purity intermediates and customized reaction conditions. Battery-related consumption, meanwhile, is influenced by industrial IoT deployments, remote monitoring equipment, defense and infrastructure applications, and broader electrification strategies that favor chemistries with extended shelf life and low maintenance requirements. The report examines how these vectors interact, where demand concentration is likely to intensify, and which application segments are positioned for accelerated uptake over the forecast period.
Competitive Landscape: Positioning, Profiles, and Strategic Implications
Key Enterprise Profiles and Capability Differentiation
The Thionyl Chloride competitive environment is defined by a mix of established specialty chemical manufacturers, regional producers with integrated synthesis capabilities, and reagent-grade suppliers serving laboratory and high-purity research markets. The report provides structured profiles of the core companies shaping this landscape, mapping their geographic base, product focus, and strategic positioning rather than reducing them to undifferentiated competitors.
LANXESS AG, headquartered in Cologne, Germany, occupies a prominent position through its high-purity Thionyl Chloride chlorinating solutions and its relevance to long-life Li-SOCl2 battery electrolytes. Its portfolio spans pharmaceutical, agrochemical, and specialty synthesis applications, giving it cross-sector leverage that aligns with both industrial and advanced battery demand. Merck KGaA, based in Darmstadt, Germany, complements this landscape with reagent-grade Thionyl Chloride at 97 percent purity, targeting laboratory environments and specialty chemical synthesis where consistency and analytical-grade reliability are paramount. Its U.S. affiliate, Sigma-Aldrich Co. LLC, extends this reach across research and organic synthesis applications from St. Louis, Missouri, reinforcing the importance of reagent-grade channels in the broader market architecture.
In the Asia-Pacific and emerging manufacturing corridors, companies such as Jiangxi Selon Industrial Co. Ltd. and Shandong Kaisheng New Materials Co. Ltd. reflect the growing sophistication of regional fine chemical and specialty materials producers. Jiangxi Selon's Thionyl Chloride offerings span pharmaceutical, agrochemical, and industrial synthesis use cases, while Shandong Kaisheng concentrates on organic synthesis and intermediate production within the specialty materials domain. These profiles illustrate how regional capacity is increasingly aligned with downstream formulation needs rather than commodity-style volume alone.
Indian manufacturers add further structural diversity. Transpek Industries Ltd. manufactures Thionyl Chloride for agrochemicals, pharmaceuticals, and specialty chemical intermediates, while Bodal Chemicals Ltd. produces the chemical for pesticide, pharmaceutical, and fine chemical intermediates. Both profiles underscore India's expanding role as a synthesis and intermediate supply hub. CABB Group, based in Germany, rounds out the competitive set as a supplier of Thionyl Chloride and related chlorinating agents for industrial and agrochemical applications, reinforcing Europe's continued relevance in high-specification chlorination chemistry.
Concentration Dynamics and Strategic Interpretation
Market concentration is a critical lens for understanding pricing power, supply reliability, and the pace at which new entrants can scale. The report frames concentration through a measured concentration ratio environment, where the leading cohort holds meaningful but not prohibitive share. This structure suggests a market in which scale, technical differentiation, and application-specific compliance capabilities matter more than sheer volume dominance. For buyers, it signals the importance of multi-source qualification and supplier diversification. For producers, it highlights the strategic value of grade specialization, battery-grade consistency, and regional distribution strength.
Rather than treating concentration as a static statistic, the analysis connects it to operational realities: how grade-level positioning influences customer stickiness, how regional manufacturing proximity affects logistics and lead-time reliability, and how reagent-grade versus technical-grade portfolios create distinct margin and demand profiles. This framing allows executives to interpret competition not as a ranking table but as a map of capability overlaps and whitespace opportunities.
Regulatory and Supply Chain Dynamics Shaping 2026
Regulatory Realignment in Key Manufacturing Markets
Regulatory shifts can reorganize trade flows, alter qualification timelines, and change the economics of battery-related chemical distribution. A notable development affecting the 2026 outlook is the optimization of import and export measures for lithium thionyl chloride batteries containing no more than one kilogram of Thionyl Chloride. Effective January 1, 2026, licensing requirements for these battery configurations are removed under the coordinated policy framework announced in December 2025 by MIIT, MOFCOM, and GAC China.
For market participants, this change is strategically significant because it lowers procedural friction for a defined battery segment that relies on Thionyl Chloride electrolytes. It can accelerate cross-border movement of compliant battery products, influence sourcing decisions for OEMs and integrators, and reshape the competitive balance between exporters and domestic manufacturers in segments previously constrained by licensing overhead. The report contextualizes this development within broader regulatory trends, helping stakeholders distinguish between temporary administrative relief and structural market opening.
Thionyl Chloride Market
Feedstock Realities and Production Architecture
Thionyl Chloride production is fundamentally linked to sulfur dioxide trioxide and sulfur dichloride chemistry, with sulfur dichloride serving as the primary feedstock. The availability and cost dynamics of this feedstock are shaped by refining byproducts and broader chlorination supply chains, making production economics sensitive to upstream industrial activity as well as regional processing capacity. Understanding this dependency is essential for anticipating margin pressure, supply continuity, and the timing of capacity adjustments.
The research integrates these feedstock realities into the market narrative rather than treating them as peripheral technical notes. By connecting synthesis pathways to production constraints and downstream demand, the analysis gives procurement and operations teams a clearer basis for evaluating supplier resilience, lead-time variability, and the likelihood of regional price divergence. This is particularly relevant for enterprises that depend on stable Thionyl Chloride supply for pharmaceutical intermediates, agrochemical production, and battery electrolyte formulations.
Report Architecture: What Decision-Makers Will Gain
Scope, Segmentation, and Analytical Depth
This market research is structured to support both strategic planning and tactical execution. It provides a full historical reconstruction from 2020 to 2025, a clearly defined 2026 baseline, and a forward forecast extending to 2032. All monetary values are presented in USD, with revenue expressed in millions, enabling consistent financial modeling and cross-market comparison. The report integrates segmentation by region, by grade, and by application, allowing stakeholders to isolate the demand structures most relevant to their operational footprint without losing sight of total market context.
Crucially, the report does not stop at segmentation tables. It interprets how regional demand patterns reflect manufacturing localization, how grade-level splits differentiate technical-grade volume from pharmaceutical- and reagent-grade value, and how application-level consumption ties back to product lifecycle, regulatory environment, and end-use durability. This interpretive layer is what separates a data catalog from a strategic asset. For readers who need to understand not only where the market is going, but why certain pathways are more defensible than others, that depth is essential.
Competitive Intelligence and Operational Context
Beyond macro forecasts, the publication delivers company-level intelligence that can inform sourcing strategy, partnership evaluation, and competitive benchmarking. Enterprise profiles are paired with capability summaries that clarify which players serve which demand environments, where high-purity and reagent-grade offerings command differentiated positioning, and how regional producers are building relevance in pharmaceutical, agrochemical, and specialty synthesis markets.
Worldwide Lithium Thionyl Chloride Cell Market
The report also incorporates industry context that affects day-to-day decision-making, including regulatory updates, feedstock dependencies, and the operational implications of battery-related policy changes. By weaving these elements into a unified analytical narrative, the research helps executives anticipate disruptions, validate assumptions, and adjust commercial plans with greater precision. The goal is not simply to inform, but to reduce uncertainty in capital allocation, supplier selection, and market-entry timing.
Strategic Takeaways for 2026 Planning
As organizations finalize 2026 objectives, Thionyl Chloride market intelligence must serve as more than background context. It should directly Shape procurement diversification, grade-level portfolio decisions, and application-specific investment prioritization. The report's central value proposition is that it converts a growing but complex market into a structured decision framework.
Several strategic imperatives emerge from the analysis. First, demand resilience across pharmaceutical, agrochemical, organic synthesis, and battery applications means that supply continuity and grade consistency should be treated as core risk-management priorities rather than operational afterthoughts. Second, the regulatory relaxation affecting specific lithium thionyl chloride battery configurations introduces new trade-flow possibilities that reward early mapping of supply routes and compliance pathways. Third, the concentration structure of the market suggests that differentiation through purity, reliability, and application expertise will remain more lucrative than competing on undifferentiated volume alone.
For investors and corporate strategists, the forecast horizon through 2032 offers a practical basis for long-cycle planning. The steady compound growth trajectory, combined with shifting regulatory and feedstock conditions, creates a market environment in which disciplined forecasting and scenario readiness outperform reactive adjustments. Enterprises that use this research to align product development, sourcing, and geographic exposure with verified market signals will be better positioned to capture value as the Thionyl Chloride Market continues its measured expansion.
PW Consulting's Thionyl Chloride Market report is designed for leaders who require precision, context, and forward visibility in a single analytical package. It provides the structural understanding necessary to navigate 2026 with confidence and the segment-level intelligence required to make informed, defensible decisions across the forecast period.
For detailed analysis of this topic, please visit the official page: Thionyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com